THE SUMMARYAI-generated
Apple Stock Analysis: Bank of America Securities
Key Concepts:
- Apple stock valuation and potential upside
- Headwinds affecting Apple's stock: tariffs, Google payment issue, AI rollout
- Services revenue growth and its impact on Apple's valuation
- iPhone cycles and their influence on gross profit
- Installed base growth in emerging markets
- Monetization of the installed base through services penetration
- Law of large numbers and Apple's market capitalization potential
Current Valuation and Potential Upside
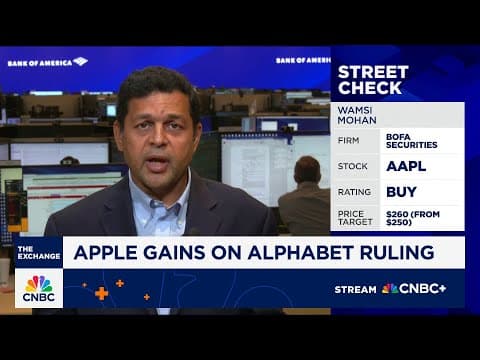
- Bank of America Securities analyst Wamsi Mohan believes Apple shares are attractively valued despite recent underperformance.
- The stock experienced an 11% increase in August, signaling a potential recovery.
- Mohan's price target for Apple is $250, indicating a bullish outlook, although not aggressively so.
Headwinds Affecting Apple's Stock
- Tariffs: Previously a significant headwind, the tariff issue is now considered less of a concern, potentially freeing up $1.1 billion in incremental cost savings.
- Google Payment Issue: The ongoing issue with Google payments remains an overhang on the stock, primarily affecting the multiple rather than earnings. The outcome is still uncertain ("TBD").
- AI Narrative: Apple's AI strategy, particularly at the edge, is taking longer to materialize than expected. A "botched rollout of AI" led to increased investment in developing an AI-enabled iPhone, expected to drive upside in two years.
Services Revenue Growth
- Services contribute more to gross profit than iPhone, a trend expected to continue.
- The installed base of iPhones is 1.2 billion, but only 300 million are paying subscribers, with only 30 million contributing the majority of services revenue.
- Significant opportunity exists to increase penetration within the existing subscriber base and expand the install base itself.
- Double-digit services growth is anticipated for the foreseeable future, driven by increased penetration, a growing install base, and pricing power.
- Services gross margins at 75% are expected to dominate and eventually exceed product gross profit within five years.
- The increasing importance of services reduces the stock's volatility, limiting potential earnings shortfalls to around 10% even with adverse product news.
iPhone Cycles and Future Trends
- A strong iPhone cycle is anticipated in the fall of 2026, potentially driven by the intersection of AI and foldable form factors.
- This could temporarily lead to iPhone gross profits exceeding services gross profits for a quarter or so.
Installed Base Growth in Emerging Markets
- Emerging markets are identified as the next major driver of installed base growth.
- The shift from cash-based to credit-based economies in these markets makes iPhones more affordable.
- Strong brand value in emerging markets remains largely untapped.
Monetization of Installed Base
- Significant room exists to monetize the existing installed base through increased services penetration.
- Currently, only 30 million out of 1.3 billion users are significantly contributing to services revenue.
Law of Large Numbers and Market Capitalization
- The discussion of the "law of large numbers" is revisited, questioning how much higher Apple's market capitalization can go.
- Apple's market cap was close to $3 trillion at its high.
- Growth potential is viewed from two perspectives: continued growth of the install base and monetization of that base.
Notable Quotes
- "Apple shares are pretty attractively valued." - Wamsi Mohan
- "We've said consistently [Apple] will be a winner on AI at the edge." - Wamsi Mohan
- "Double digit services growth we believe very strongly in that for the foreseeable future." - Wamsi Mohan
Technical Terms and Concepts
- Mag-7: Refers to the seven largest technology companies in the stock market.
- Multiple: A valuation metric used to assess a company's stock price relative to its earnings or other financial metrics.
- AI at the edge: Refers to processing AI tasks on the device itself rather than relying on cloud-based processing.
- Installed base: The total number of active devices running a particular operating system or using a specific product.
- Penetration: The extent to which a product or service is used within a particular market or segment.
- Gross Profit: Revenue less the cost of goods sold.
Conclusion
Bank of America Securities maintains a bullish outlook on Apple, citing attractive valuation, the potential for services revenue growth, and expansion in emerging markets. While acknowledging near-term headwinds related to tariffs, the Google payment issue, and AI rollout, the analyst believes that Apple's long-term prospects are strong, particularly driven by the increasing importance of services and the untapped potential in emerging markets. The increasing contribution of high-margin services is expected to reduce volatility and potentially lead to a higher valuation multiple for the stock.
AI summaries can miss context or contain errors. Check important details against the original video.
MAKE IT YOURS
Free tools