Macroeconomic Business Cycle Mechanisms
Key Concepts: Business Cycles, Dual Mandate (Federal Reserve - Maximum Employment & Price Stability), Geopolitical Conflict, S&P 500, Unemployment Rate, Inflation Rate, Interest Rates (Fed Funds Rate), Money Supply (M2), Oil Prices, Negative Feedback Loop, Recession, Checkmate (Federal Reserve Policy).
I. Introduction & Context: Late Business Cycle Characteristics
The video focuses on the mechanisms that typically conclude business cycles, building on previous discussions about the current late-cycle environment. A key characteristic of this late stage is a “rolling down the risk curve,” where investors shift from higher-risk assets to lower-risk ones: altcoins to Bitcoin, Bitcoin to stocks, stocks to gold. The analysis centers around the interplay between macroeconomic factors, specifically the unemployment rate and inflation rate – the Federal Reserve’s dual mandate – and the increasingly significant influence of geopolitical conflict.
II. Identifying Business Cycles & The Developed Metric
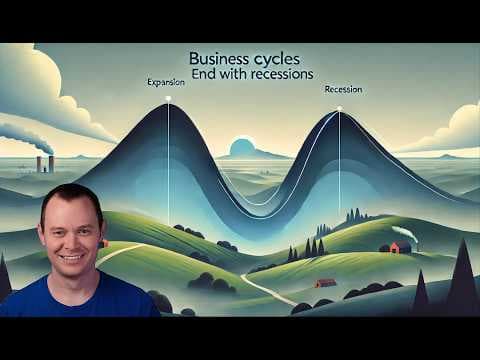
The presenter argues that commonly perceived recessions don’t always represent true business cycle ends. He introduces a proprietary business cycle indicator calculated as: S&P 500 / (Unemployment Rate Squared) * Inflation Rate * Fed Funds Rate, normalized by the M2 money supply. This metric, when charted, reveals that business cycles are longer-term phenomena, lasting many years, rather than occurring every few years as some believe. The current cycle is argued to have begun either with the pandemic (if considered a “black swan” event) or as early as 2009. The chart demonstrates that business cycles consistently return to low levels on this metric, indicating a recessionary endpoint. Currently, the index is around 58-59, suggesting a potential for decline.
III. The Role of Geopolitical Conflict & Oil Prices
While the unemployment and inflation rates are central to the Federal Reserve’s mandate, the video highlights geopolitical conflict as a crucial third factor influencing business cycles. Specifically, the presenter emphasizes the correlation between spikes in oil prices and the beginning of the end of business cycles. Historical examples are cited:
- 1990: Oil spike preceded the 1990 recession.
- 2000: Oil spike preceded the 2001 recession.
- 2008: Oil spike preceded the 2008 financial crisis.
- 2016: Oil price increase, though less definitive due to other factors (inverted yield curve).
The current situation is analyzed in the context of recent geopolitical tensions in the Middle East, raising the question of whether a similar oil price spike is imminent.
IV. The Negative Feedback Loop & Current Economic Conditions
The presenter explains that a recession doesn’t occur immediately upon an oil price spike. Instead, a negative feedback loop must develop: a drop in the stock market leads to company layoffs, which reduces overall demand, causing further layoffs. This cycle is not currently in motion. Key indicators supporting this assessment include:
- Stock Market: Remains at all-time highs.
- Initial Claims: Remain low.
- Layoffs: Remain low relative to historical standards.
However, the potential for this loop to initiate in the coming years is acknowledged.
V. Federal Reserve “Checkmate” Scenario
The video introduces the concept of the Federal Reserve being “checkmated” – a situation where it lacks effective tools to address simultaneous economic pressures. The Fed can typically manage either rising unemployment (by cutting rates) or rising inflation (by raising rates). However, if geopolitical conflict drives up oil prices while the unemployment rate is also increasing, the Fed faces a dilemma. Addressing unemployment with rate cuts would exacerbate inflation, while controlling inflation with rate hikes would worsen unemployment. This dual pressure represents the “checkmate” scenario. The presenter believes this situation could arise within the next one to two years.
VI. Leading Indicators & Market Uncertainty
The presenter notes that the S&P 500 has stalled since October, attributing this to market uncertainty. He references historical patterns, noting that weakness typically becomes more pronounced by late March/early April in midterm years. He also highlights the following leading indicators:
- Job Openings: Decreasing.
- Hiring: Decreasing.
- Quits: Decreasing.
- Unemployment Rate: Slowly increasing (but not yet at a critical nonlinear phase).
He cautions against attributing potential layoffs solely to AI, suggesting overhiring during the pandemic may be a more significant factor, with AI potentially used as a convenient narrative.
VII. Conclusion & Long-Term Perspective
The video concludes by reiterating that business cycle transitions are lengthy processes, taking years to unfold. The current environment is characterized by a late-cycle dynamic, and a reset is likely necessary for sustained economic improvement. The presenter emphasizes the importance of understanding these long-term trends, rather than reacting to short-term market fluctuations. He notes that higher-risk assets have underperformed for an extended period due to this late-cycle environment. He encourages viewers to stay informed and utilize resources like ITC Premium and benjaminc.com for further analysis.
Notable Quote:
“Markets absolutely hate uncertainty and when you are in an environment with a lot of uncertainty, they tend to stall out.” – The Presenter.
This summary aims to provide a detailed and precise account of the video’s content, maintaining the original language and technical terminology. It focuses on actionable insights and specific details, rather than broad generalizations.
AI summaries can miss context or contain errors. Check important details against the original video.