Key Concepts
Debt machine, credit card companies, buy now pay later (BNPL) services, transaction fees, interest rates, late fees, psychological traps, friction, dopamine activation, present bias, underestimation bias, financial denial, algorithmic matching, gamification, cognitive overload.
The Debt Machine: How Credit Card Companies and BNPL Services Make Money
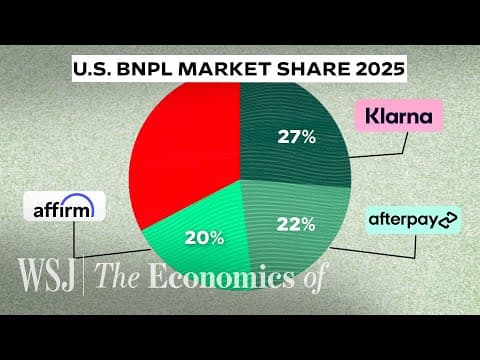
The video focuses on how credit card companies (Visa, Mastercard, American Express) and buy now pay later (BNPL) services (Clarna, Afterpay, Affirm) exploit consumer psychology to encourage spending and generate revenue.
1. Transaction Fees:
- Both credit card companies and BNPL services charge merchants a percentage of each transaction.
- Credit card companies typically charge 2-3%, while BNPL services charge higher fees, typically 4-6%.
- Example: A $100 purchase results in a $3-$6 fee for Visa or Clarna.
- Merchants are willing to pay these fees because BNPL options increase sales by reducing purchase hesitation. Studies show people spend more per transaction, buy impulsively, and pay higher prices when using cards or BNPL.
2. Interest and Fees:
- Credit cards advertise 0% interest, but this is conditional on timely payments. Late payments trigger late fees, penalties, and high interest rates (over 23% APR in some cases).
- BNPL services also charge fees and interest for missed payments, potentially damaging credit scores.
- The business model relies on less reliable customers who miss payments. Wealthier customers who consistently pay are charged low or no interest because the companies profit from the transaction fees on their large purchases.
- Analogy: Similar to a casino, high rollers receive VIP treatment, while those with limited funds are charged for everything.
The Psychology of Debt: Traps and Exploitations
The video details several psychological traps that credit card companies and BNPL services use to encourage spending:
1. Friction:
- Paying with cash feels more "real" due to the physical exchange and mental calculation involved.
- Credit cards and mobile payments reduce friction, making spending feel less painful.
- Study: People spend more when using cards instead of cash.
- These payment methods act as "painkillers," reducing the perceived cost of spending.
2. Dopamine Activation:
- The act of buying triggers a dopamine release in the brain, creating a feeling of satisfaction.
- This pathway is similar to those activated by social media, sugar, and gambling, leading to addictive spending habits.
- Credit card companies and BNPL services design their user experiences to be as addictive as possible, encouraging users to chase the dopamine hit.
3. Present Bias:
- The human brain prioritizes immediate gratification over future consequences.
- BNPL services exploit this by emphasizing the "buy now" aspect and downplaying the "pay later" aspect.
- The immediate reward of acquiring the item outweighs the future pain of repayment.
4. Underestimation Bias:
- Consumers tend to underestimate future financial difficulties, assuming they will be able to afford payments later.
- Credit cards capitalize on this optimism by offering credit limits that users push, believing they can repay the balance next month.
5. Financial Denial:
- BNPL services normalize debt by presenting it as a convenient feature rather than a loan.
- The lack of a formal application process or loan officer reinforces the perception that it's not real debt.
- Example: Choosing Clarna at checkout on ASOS feels like splitting payments, not taking out a loan.
6. Algorithmic Matching:
- BNPL services use algorithms to personalize offers based on individual spending habits and preferences.
- They track user behavior and tailor offers to trigger the "why not?" response, making them feel irresistible.
- The goal is to make users feel like accepting the deal was their own idea.
7. Gamification:
- Credit card companies use tiered systems (e.g., Green, Gold, Platinum, Black) to create a sense of progression and reward spending.
- BNPL services increase spending limits after successful repayments, making users feel like they have earned something.
- This behavioral conditioning turns financial behavior into a reward loop, similar to a video game.
8. Cognitive Overload:
- BNPL services create multiple mini-loans for each purchase, requiring users to manage numerous payment plans.
- This cognitive overload overwhelms the brain, leading to avoidance and missed payments.
- This is a deliberate business model, not a bug.
Conclusion
Credit card companies and BNPL services strategically exploit psychological vulnerabilities to encourage spending and profit from transaction fees, interest, and late fees. Understanding these tactics is crucial for avoiding debt traps and making informed financial decisions. The video emphasizes the importance of intentionality in managing finances and avoiding autopilot behavior.
AI summaries can miss context or contain errors. Check important details against the original video.