Key Concepts
Buy Now, Pay Later (BNPL), Installment Payments, Consumer Debt, Financialization, Social Media-Driven Consumption, Post-Pandemic Spending Boom, Financial Literacy, Pain of Paying, Temporal Discounting, Artificial Urgency, Loan Stacking, Merchant Fees, Late Fees, Data Harvesting.
The Allure and Danger of Buy Now, Pay Later (BNPL)
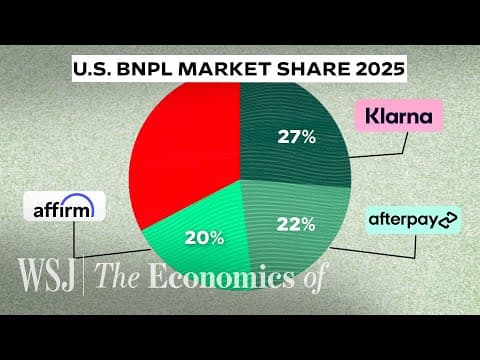
The video explores the increasing popularity and potential pitfalls of Buy Now, Pay Later (BNPL) services like Affirm, CLA, and Afterpay. It highlights how these services, which allow consumers to split purchases into installments, are contributing to rising consumer debt and exploiting psychological vulnerabilities.
The Rise of BNPL and its Context
- Explosive Growth: BNPL transaction volume has surged from $2 billion in 2019 to a projected $122 billion in 2025.
- Cultural Shifts: This growth is attributed to:
- Financialization of Everything: The tendency to finance even small purchases.
- Social Media-Driven Consumption: Influencers promoting luxury lifestyles, making BNPL appealing for aspirational purchases.
- Post-Pandemic Spending Boom: Consumers using BNPL for "revenge spending."
- Declining Financial Literacy: Especially among young adults, exacerbates the problem.
BNPL vs. Credit Cards: A Seemingly Better Deal?
The video contrasts BNPL with traditional credit cards, highlighting perceived advantages:
- Instant Approval: BNPL offers quick approval compared to the credit check required for credit cards.
- 0% Interest: BNPL often advertises interest-free payments, unlike credit cards with high APRs (19-23%).
However, the video emphasizes that this "interest-free" aspect is conditional:
- Late Fees: Missed payments result in late fees, ranging from $2 to $15 or even up to 25% of the purchase value.
How BNPL Companies Make Money
The video details the revenue streams for BNPL companies:
- Merchant Fees: Charging retailers 4-6% of the transaction price, significantly higher than traditional credit card processing fees (around 2.5%).
- Late Fees: A substantial revenue source, as one in three BNPL users miss a payment at least once.
- Data Harvesting: Collecting and selling user data from checkout pages to other brands for targeted marketing.
- Debt Securitization: Packaging and selling consumer debt to larger financial institutions.
Psychological Manipulation at the Checkout Page
The video explains how BNPL services use psychological tricks to encourage spending:
- Pain of Paying: Splitting costs into installments reduces the perceived financial pain.
- Temporal Discounting: Emphasizing immediate rewards ("Pay just $25 today") over future costs.
- Artificial Urgency: Creating a sense of limited-time offers to rush decisions.
- Visual Cues: Using bright colors and pre-selected options to guide users towards BNPL.
The Dangers of Loan Stacking and Overextension
- Loan Stacking: Taking out multiple BNPL loans simultaneously, often without realizing the total debt. In 2022, 63% of BNPL borrowers had more than one loan at a time.
- Financing Small Purchases: Using BNPL for everyday items like groceries or fast food, leading to a rapid accumulation of debt. Example: CLA on DoorDash allowing financing of a $15 burrito.
- Targeting Financially Vulnerable Individuals: BNPL programs often target those with limited financial literacy and existing credit card debt. 69% of BNPL users are already in credit card debt, and 28% are between 18 and 24 years old.
Responsible BNPL Usage: Recommendations
The video concludes with advice for consumers:
- Never Spend More Than You Have: The cardinal rule for avoiding debt.
- Treat BNPL Like Cash: If you spend $100, consider it $100 directly out of your bank account.
- Avoid Loan Stacking: Refrain from financing weekly expenses.
- Use BNPL Strategically (If Confident): If you are financially literate, use BNPL to earn interest on your cash while paying off the purchase.
Notable Quotes
- "I literally once financed a bottle of body wash." - Illustrates the extreme use of BNPL.
- "It's crazy because buy now, pay later is so easy to do, people are starting to use it on more and more occasions where it's really not meant to be used." - Highlights the overextension of BNPL usage.
- "These companies spend millions of dollars on psychological research to get you to spend more than you can actually afford, but now you know a little bit more about how to protect yourself." - Summarizes the video's core message.
Conclusion
BNPL services offer convenience and the illusion of affordability, but they can easily lead to overspending and debt, especially for those with limited financial literacy. By understanding the psychological tactics employed by BNPL companies and practicing responsible spending habits, consumers can mitigate the risks and make informed financial decisions. The key takeaway is to treat BNPL as a direct extension of your existing finances and avoid accumulating multiple loans for non-essential purchases.
AI summaries can miss context or contain errors. Check important details against the original video.