Key Concepts
- Value Investing Framework: A three-part methodology for evaluating stocks: Growth, Distributable Cash Flows, and Multiple Change.
- Growth: The projected rate at which a company will increase its revenues, determined by historical data, management guidance, analyst expectations, and industry/ecosystem trends.
- Distributable Cash Flows (Owner Earnings): The surplus cash a company generates that can be distributed to shareholders (dividends, share repurchases), accounting for cash efficiency.
- Multiple Change (Valuation): The assessment of a company's current valuation (using ratios like EV/EBIT, PE) compared to historical averages and peers, and the projected change in this multiple.
- Risk Profile: An assessment of the probability that actual results will be materially worse than projected, aiming for investments with a high probability of surpassing a 10% average annual return.
- CAGR (Compound Annual Growth Rate): A measure of the average annual growth rate of an investment over a specified period.
- Moat: A sustainable competitive advantage that protects a company's long-term profits and market share.
- Multiple Contraction/Expansion: A decrease or increase in valuation multiples (e.g., EV/EBIT, PE) over time.
Stock Analysis Framework
The video presents a practical framework for evaluating publicly traded companies, refined over a decade of market outperformance and extensive reading. This framework consists of three core components that drive shareholder returns:
-
Growth: This involves determining a company's projected revenue growth rate for the next few years. The analysis combines quantitative and qualitative metrics:
- Historical Growth: Examining past performance to assess its extrapolability.
- Management Guidance & Analyst Expectations: Considering company forecasts and external expert opinions.
- Industry & Ecosystem Trends: Analyzing the growth of the industry and identifying any mega-trends that could impact the company. The principle is that it's easier to grow in a growing industry than a declining one.
-
Distributable Cash Flows (Owner Earnings): This component focuses on the surplus cash a company generates that can be distributed to shareholders through dividends or share repurchases. It accounts for companies' varying cash efficiency, distinguishing between those that reinvest heavily and those that can return cash.
-
Multiple Change (Valuation): This part assesses the company's current valuation using key ratios like EV/EBIT and PE, comparing them to historical averages and peers. These figures serve as a starting point, with an estimation of future profit margins to identify a potential gap between current and intrinsic valuation.
The yearly return for a stock is calculated by summing these three components: Growth + Distributable Cash Flows + Multiple Change = Yearly Return. A standard analysis period of three years is used.
Finally, a Risk Profile is added to ensure apples-to-apples comparisons. This assesses the probability of materially worse outcomes than projected and aims for investments with a high probability of exceeding the historical market average return of 10%. The preference is for a safe 15% return over a speculative 25%.
Apple Analysis
- Main Topics: Apple's current valuation, growth prospects, and distributable cash flows in the context of its market position and historical performance.
- Key Points:
- Apple is a "behemoth," with size acting as a gravitational force on growth.
- Historical 10-year CAGR is 8.5%, used as a maximum for future projections.
- Analysts expect 6% annual growth for the next two years.
- iPhone accounts for half of Apple's sales; the global smartphone industry is projected to grow at 4% annually until 2030 (Spherical Insights).
- Apple's market share is around 20% (Statista) and has been stable, with recent gains.
- To achieve near historical growth, Apple needs to rely on non-iPhone products and services.
- Projected growth rate for the next three years is 6%, balancing industry growth, analyst forecasts, and historical averages, with potential boosts from new products (goggles) and AI.
- Distributable cash flows are around 5% annually, from stock repurchases (nearly 5%) and a small dividend, slightly offset by increased net debt.
- Current valuation: EV/EBIT 24, PE 30, higher than 5-year (EV/EBIT 20.5, PE 26) and 10-year (EV/EBIT 15, PE 20.5) historical averages.
- Justification for higher valuation is linked to AI and goggles, but analyst growth expectations are lower than historical averages, suggesting no reason to pay more for current earnings.
- Expected return to 5-year historical average valuation (EV/EBIT 20.5, PE 26) implies a 7% annual multiple contraction over three years.
- Assumptions are conservative, with a low risk of materially worse outcomes. Recession impact is expected to be short-lived.
- Expected 3-Year CAGR: 6% (Growth) + 5% (Distributable Cash Flows) - 7% (Multiple Contraction) = 4%.
- Risk Profile: Low.
- Notable Statements: "Apple is one of the greatest companies in the world. It's not the company that we have an issue with here, but rather the price of Apple's stock." "We'd happily put up a ton of our money in this company if only it would trade at lower multiples."
- Conclusion: Apple's current valuation is too high for an attractive investment, despite being a quality company. It is crowned "King of the Hill" for now due to its strength, but not as a top investment pick at current prices.
Microsoft Analysis
- Main Topics: Microsoft's growth drivers (AI, cloud), distributable cash flows, valuation, and competitive advantages compared to Apple.
- Key Points:
- 10-year historical CAGR: 10.5%, with recent acceleration.
- Analysts expect 13% annual growth for the next three years, fueled by AI.
- Cloud services (Azure) and Office package are key segments. Azure accounts for one-third of sales and has grown by 28% annually, with industry growth projected at 15% CAGR until 2030.
- Windows remains the dominant OS, with macOS gaining market share but posing a moderate threat.
- Projected growth rate for the next three years is 12%, between analyst expectations and historical growth, acknowledging size as a limiting factor.
- Distributable cash flows are 2.5% annually, from share repurchases (over 1%) and dividends (around 1%), with a slight decrease in net debt.
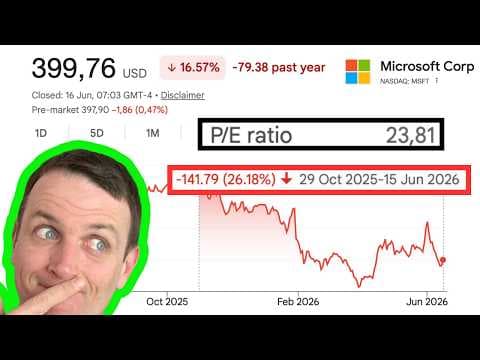
- Current valuation: EV/EBIT 26.5, PE 33, close to 5-year averages (EV/EBIT 26, PE 31.5).
- Profit margins are at 20-year highs (42%) and are expected to remain stable.
- Valuation is projected to contract slightly to EV/EBIT 25 (below 5-year average) over three years, reflecting a slowdown in growth from 15% to 12%. This equates to a ~2.5% annual multiple contraction.
- Microsoft is considered slightly riskier than Apple in assumptions but deserves a higher multiple due to expected faster growth and lower sensitivity to economic cycles.
- Microsoft's moat is considered wider than Apple's due to near-monopolistic positions in Office and OS (over 70% market share for decades).
- Resilience to recessions is noted, with minimal sales decline during the 2008-2009 financial crisis.
- Expected 3-Year CAGR: 12% (Growth) + 2.5% (Distributable Cash Flows) - 2.5% (Multiple Contraction) = 12%.
- Risk Profile: Slightly higher than Apple but not by much.
- Conclusion: Microsoft is projected to outperform Apple significantly (8% higher CAGR) and is therefore crowned the new "King of the Hill."
Tesla Analysis
- Main Topics: Tesla's explosive growth, challenges in cash flow generation, stratospheric valuation, and significant risks.
- Key Points:
- Historical growth is not a reliable indicator due to its explosive nature.
- Analysts expect an average growth rate of 25% for the next three years.
- Tesla holds about 20% of the EV market share.
- The EV industry is projected to grow at 25% CAGR until 2030, aligning with Tesla's expected growth.
- Distributable cash flows are negative (-4% annually) due to high reinvestment needs (CapEx, inventory) and shareholder dilution (4.5% annually), partially offset by debt reduction.
- Current valuation: EV/EBIT 61, PE 70, considered "stratospheric."
- Competitors (Toyota, VW, Mercedes, BMW, GM) trade at EV/EBIT 9-15.
- The EV market growth is at the expense of combustion cars; the overall auto industry growth is limited.
- Valuation is expected to contract significantly as growth slows. A generous projection for three years out is EV/EBIT 40 and PE 50, assuming a 16.5% operating margin.
- This implies an 8% annual multiple contraction over the next three years.
- Risk Profile: Very high. Assumptions are riskier due to potential for recession impact, tougher competition, loss of market share, slower EV industry growth, and dependence on subsidies.
- Self-driving business upside is uncertain and its widespread adoption is at least half a decade away, requiring heavy discounting.
- Tesla's valuation is high even compared to Microsoft, despite Microsoft's wider moat, higher cash flow generation, and less cyclical nature.
- Tesla's market cap is comparable to all other auto manufacturers combined, despite holding only 20% of the EV market.
- The projected 16.5% margin is the highest ever for Tesla, and its sustainability is questioned given competition and continued investment.
- Expected 3-Year CAGR: 25% (Growth) - 4% (Distributable Cash Flows) - 8% (Multiple Contraction) = 13%.
- Risk Profile: High.
- Conclusion: Despite a higher projected CAGR (13%) than Microsoft (12%), the significant uncertainties and high risk profile make Tesla a less attractive investment. Microsoft remains the "King of the Hill."
Bonus: Betson Analysis
- Main Topics: Analysis of a specific stock holding (Betson) with a focus on its growth, cash flow, valuation, and risk profile, presented as a superior alternative to the analyzed tech giants.
- Key Points:
- Historical Growth: 10% revenue CAGR over the last 10 years with low variance.
- Analyst Forecasts: 9-10% average growth for the next three years.
- Industry Growth: Online gambling industry projected at nearly 12% CAGR until 2030 (Grand View Research).
- Projected Growth: 9% annual growth for the next three years.
- Distributable Cash Flows: 7% annually, with most returned as dividends and some used for bolt-on acquisitions. None of this is required to maintain the 9% growth.
- Valuation: EV/EBIT 7, PE 8.5. This is lower than historical averages (EV/EBIT 8.5, PE 9.5), which are considered too low given operational excellence and track record.
- Reasons for Low Valuation: ESG movement and a portion of sales from Turkey.
- Expected Multiple Expansion: Hesitant to forecast significant movements but believes EV/EBIT 9 is achievable, translating to about 6% annual multiple expansion. This is driven by growing international investor interest and a decreasing reliance on the Turkish market.
- Risk Profile: Low.
- Biggest Risks: Growth rate and the Turkish market, but the company has operated there for a decade, providing some "linda effects" (resilience). Regulatory risks are mitigated by geographical diversification.
- Expected 3-Year CAGR: 9% (Growth) + 7% (Distributable Cash Flows) + 6% (Multiple Expansion) = 22%.
- Risk Profile: Low.
- Notable Statement: "Price is what you pay, value is what you get."
- Conclusion: Betson is presented as a superior investment compared to Microsoft, offering a projected 22% annual return with a low risk profile, versus Microsoft's 12% with a less compelling margin of safety. Betson is identified as the Swedish online gambling company Betsson.
Synthesis/Conclusion
The video provides a practical, three-part framework (Growth, Distributable Cash Flows, Multiple Change) for analyzing stocks, augmented by a risk assessment. Applying this framework to Apple, Microsoft, and Tesla reveals that despite their market dominance and quality, current valuations make them less attractive. Apple's projected 4% CAGR is deemed uninspiring due to its high valuation. Microsoft emerges as the "King of the Hill" among the tech giants with a projected 12% CAGR, outperforming Apple and demonstrating resilience. However, Tesla's projected 13% CAGR is overshadowed by its extremely high valuation and significant risks, making it a less favorable choice.
The analysis culminates in the presentation of Betson, an online gambling company, as a superior investment. Betson offers a projected 22% CAGR with a low risk profile, driven by solid historical growth, strong distributable cash flows, and an undervalued valuation with potential for multiple expansion. The core takeaway is that even the best companies can be poor investments if bought at the wrong price, and that a thorough, risk-adjusted valuation is crucial for achieving superior returns.
AI summaries can miss context or contain errors. Check important details against the original video.