Key Concepts
- Investor Background and Evolution: Gabe Marshank's journey from Yale to hedge funds, learning from legends like Lee Cooperman, Larry Robbins, Steve Cohen, and David Einhorn. His evolution from a numbers-focused analyst to a broader, more intuitive investor.
- Investment Philosophy: The importance of intellectual flexibility, understanding the "bigger picture" beyond just numbers, trusting instincts developed through experience, and the distinction between value and growth investing becoming obsolete.
- Capitalism and Bankruptcy: The role of bankruptcy as a self-correcting mechanism in capitalism.
- Technological Transformation (AI and Beyond): The transformative impact of AI on industries, the parallels with the dot-com boom, and the identification of value creation at the "edge" of networks.
- Commodities and Supply-Side Analysis: The critical importance of understanding supply dynamics in commodity investing, with supply being more knowable and variable than demand.
- Personal Investment Approach: The emphasis on "knowing thyself" as an investor, aligning investment strategies with personal strengths and risk tolerance.
Gabe Marshank's Investment Journey and Philosophy
Gabe Marshank shared his extensive background in investing, beginning with his undergraduate studies at Yale in 1997. Initially, he eschewed investment banking due to its demanding nature and sought a role in a hedge fund, a concept then unfamiliar to him. His first interview with Lee Cooperman, a notoriously tough but loyal figure, resulted in a $35,000 annual salary, significantly exceeding his expectations. Despite starting with no formal finance background (majoring in political science), Marshank proactively taught himself accounting, pursued his CFA, and learned Excel, driven by the ambition to earn more than his initial salary.
He detailed his early experiences at a hedge fund, where he began by performing menial tasks but gradually took on more analytical responsibilities. His mentor, Larry Robbins (now running Glenview Capital), recognized his potential and guided him. Marshank then spent eight years at SAC Capital with Steve Cohen, working as a generalist analyst, focusing on capital-intensive sectors like industrials, energy, and utilities. A significant career move was his relocation to London to cover European stocks, which he found helped him "get out of the noise" and refine his investment framework. Subsequently, he moved to Greenlight Capital, working under David Einhorn, whom he described as "whipsmart" and a tremendous investor.
Key Lessons from Mentors
Marshank highlighted key lessons learned from his mentors:
- David Einhorn: The crucial lesson was that "the answer is out here," emphasizing that while numbers are a starting point, true understanding comes from grasping the bigger picture and how businesses interact in the real world. This shifted his focus from solely SEC filings and sophisticated financial models to a more holistic view.
- Steve Cohen: The lesson from Cohen was about recognizing "when you're on to something huge." This involves developing an instinct, which Marshank clarified is not innate but a learned response from extensive experience ("tons and tons of reps"). He likens this to a baseball player's swing or Whitney Tilson's "Spidey sense."
Evolution of Investment Approach
Marshank discussed his personal evolution as an investor. Initially, he was drawn to value investing, learning from mentors like Lee Cooperman. However, he found that a small number of winners constituted the majority of his gains, leading him to focus on "how to just hang on to a winner." He acknowledged his biggest investment mistakes were not the ones that went to zero, but those where he "cut my gains" prematurely, even at a double. This aligns with Steve Cohen's advice to "cut your losses, but let your gains go."
He argued that the traditional distinction between "value" and "growth" investing is "asinine." He explained that value investing, in its classic sense (Graham and Dodd), applied to a different economic era. The US economy has become less capital-intensive over the last 30 years, with businesses like Google, Facebook, and AWS exhibiting defensible, high margins and minimal capital reinvestment, unlike the mean-reverting margins of older industrial models. This shift necessitates a broader approach to investing, focusing simply on "how do we make money and what are we comfortable with?"
Marshank advocates for an "iconoclastic" approach, meaning he doesn't prioritize what others think. He trusts his gut and has observed patterns repeat, looking for companies or industries where he feels he "knows how this movie ends," drawing parallels to James Bond films where the outcome is predictable despite varying details.
The Impact of Technology and AI
Marshank drew parallels between the current AI boom and the dot-com era, particularly the buildout of networking infrastructure. He noted that during the dot-com boom, the biggest companies to emerge (Google, Facebook) either didn't exist or were in nascent stages at the peak of the boom. He anticipates a similar pattern with AI, where the current focus on capital-intensive infrastructure (data centers) is the "substrate," but true value creation will come from companies that enable businesses to operate more efficiently or consumers to spend their time more pleasantly.
He identified two categories of successful companies emerging from technological shifts:
- Efficiency Enablers: Companies that help businesses operate more effectively (e.g., software for HR, sales).
- Pleasure Enhancers: Companies that improve consumer leisure time and experiences (e.g., entertainment platforms).
He sees AI as a significant productivity enhancer, potentially leading to more free time for individuals, which in turn fuels new industries like gaming. He also anticipates the rise of "Agentic AI," personal AI assistants, which could be worth trillions, but acknowledges the speculative nature of identifying these future winners.
The Role of Incumbents and Market Dynamics
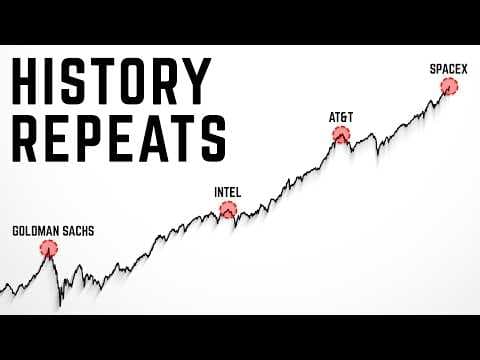
Marshank expressed skepticism about the ability of current tech giants to maintain their dominance, citing historical examples of companies that failed to adapt to new technologies (IBM with PCs, Kodak with digital photography). While acknowledging exceptions like Amazon's pivot to AWS and Netflix's transition from DVDs, he believes that the historical rule is that incumbents often fumble their leads. He pointed out that the top 10 stocks in the S&P 500 change significantly every decade, suggesting that today's leaders are not guaranteed to remain so.
He specifically discussed potential risks for current tech giants:
- Microsoft: While acknowledging its strong OS position, he noted that cloud growth, a significant driver, is becoming a commodity, facing pricing pressure.
- Amazon (AWS): Similar to Microsoft, AWS operates in a commodity-like cloud market. While Amazon is adding services, its core business faces commoditization.
- Alphabet (Google Search): He questioned the long-term viability of Google Search as a business model in an AI-driven world, anticipating competition and a shift in how information is accessed.
Marshank suggested that instead of betting on which tech giant will win, investors should focus on "what they're spending it on" and identify companies that will "take advantage of" the infrastructure being built by hyperscalers. These are companies that can leverage AI to create consumer-friendly brands with low capital requirements, focusing on delighting and amazing consumers.
Commodities and Supply-Side Analysis
Marshank emphasized the critical importance of supply-side analysis in commodity investing. He argued that supply is "much more knowable than demand" because it takes time to bring new mines or production online, providing visibility. Furthermore, supply can vary significantly, often by an order of magnitude, compared to the more incremental shifts in demand forecasts.
He used historical examples to illustrate this point:
- Iron Ore: At Greenlight Capital, they were short iron ore stocks because projected supply growth in China outpaced demand growth, leading to a price collapse.
- Lithium: A boom driven by EV demand was followed by a collapse due to a glut of supply.
- Coal: Bankruptcies in the coal industry reduced supply, leading to price spikes even as demand declined.
He discussed copper as a commodity with significant demand growth due to AI and EVs. However, he cautioned that it might not be the bottleneck. The primary bottlenecks identified were:
- Government Regulation: A seven-year process for interconnecting power facilities to the grid, with recent administrative actions making it more difficult.
- Turbine Availability: A five to six-year lead time for turbines needed for power plants, driving up stocks like GE Vernova (GEV) and Quantum Power (PWR).
Marshank also touched on the concept of the "incentivization price" for new copper mines, noting that historically, prices need to be significantly higher than the basic economic incentive to spur substantial new supply.
The Role of Bankruptcy and Capitalism
Marshank expressed a strong belief in bankruptcy as a vital "self-correcting mechanism" within capitalism. He argued that preventing bankruptcy from doing its work is often a mistake, though he acknowledged limited exceptions like the 2008 TARP rescue due to systemic risk. He views the weeding out of weaker entities as a natural and beneficial process for the stronger to thrive.
The "Know Thyself" Investment Principle
Marshank concluded with a powerful takeaway: "Know thyself," a principle attributed to the Oracle of Delphi. He stressed that the biggest mistakes investors make stem from a lack of rigorous self-honesty about their strengths and weaknesses. He posed questions to help investors assess their motivations:
- If I get this right, will I feel vindicated or lucky?
- If I get it wrong, will I feel silly or unlucky?
Investors who can operate on the "vindicated, unlucky" side of this spectrum are likely to be more successful. This involves understanding one's personality and investment style, whether it's a preference for active trading or a buy-and-hold strategy, and then adhering to that plan.
Upcoming Event and Opportunities
The discussion highlighted an upcoming event on October 29th, accessible via stansburyc.com, where Gabe Marshank will share actionable investment ideas, including a potential "10-bagger." The hosts expressed significant excitement about the current market opportunities, particularly in identifying companies that can leverage AI and other transformative technologies, moving beyond the crowded tech space to find value in "big cap great companies" and other industries. They emphasized that while AI is transformative, the real opportunity lies in identifying the companies that will exploit the infrastructure being built by hyperscalers, creating consumer-friendly services with minimal capital investment.
AI summaries can miss context or contain errors. Check important details against the original video.