Here's a comprehensive summary of the YouTube video transcript, maintaining the original language and technical precision:
Key Concepts
- Value Investing: A strategy focused on identifying undervalued securities, prioritizing risk avoidance, and generating returns from fundamentals like cash flows and dividends rather than valuation expansion.
- Valuation Expansion: The increase in a stock's price driven by a higher Price-to-Earnings (P/E) ratio or other valuation multiples, rather than by an increase in the company's underlying earnings.
- Momentum Investing: A strategy that involves buying assets that have been performing well and are expected to continue to do so, often associated with growth stocks.
- Price-to-Earnings (P/E) Ratio: A valuation metric that divides a company's stock price by its earnings per share. A high P/E ratio can indicate that a stock is overvalued.
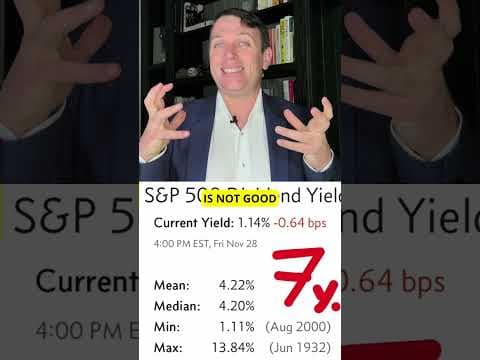
- Dividend Yield: The annual dividend payment per share divided by the stock's price.
- Cash Flow: The net amount of cash and cash equivalents being transferred into and out of a company.
- Buybacks (Share Buybacks): When a company repurchases its own shares from the open market, reducing the number of outstanding shares and potentially increasing earnings per share.
- Cyclical Stocks: Stocks of companies that tend to perform well during economic expansions and poorly during economic contractions.
- Defensive Stocks: Stocks of companies that tend to perform relatively well regardless of the economic cycle, often in sectors like food or utilities.
- ETFs (Exchange-Traded Funds): Investment funds that trade on stock exchanges, typically tracking an index.
- VIX Index (Volatility Index): A measure of the stock market's expectation of volatility based on S&P 500 index options.
- Private Equity: Investment funds that invest in companies not listed on public exchanges.
- Hedge: An investment or strategy designed to reduce the risk of adverse price movements in an asset.
- Put Option: A contract that gives the buyer the right, but not the obligation, to sell an asset at a specified price on or before a certain date.
Value Investing in the Current Market Environment
Sven Carlin of Modern Value Investing argues that value investing remains the correct approach, even amidst the recent dominance of momentum and large-cap tech stocks. His core rationale is to avoid significant losses that can occur when market bubbles burst. While acknowledging that the S&P 500 has delivered strong returns (15% per year over the last seven years), Carlin highlights that his own portfolio achieved similar returns with a significantly lower P/E ratio (10 vs. 30 for the S&P 500) and higher dividend yields (5-6%). This allows him to derive returns from fundamentals like cash flows and dividends, rather than relying on valuation expansion.
The Problem with Valuation Expansion
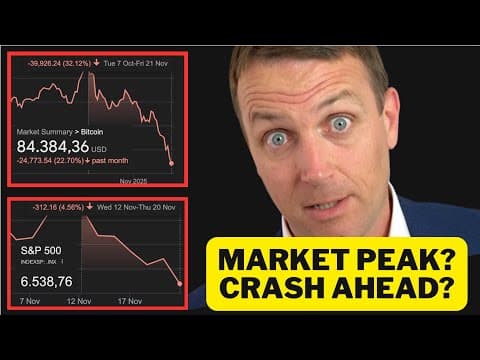
Carlin points out that the P/E ratio of the S&P 500 has risen from below 20 to above 30 over the past decade. He estimates that over 50% of market gains are attributable to this valuation expansion, not necessarily to real earnings growth. He believes that while the market is currently happy as long as the "party is going," there's a significant risk of this party ending, a scenario he wishes to avoid.
Perspective on Tech and AI Stocks
While acknowledging the quality of businesses like Microsoft, Amazon, and Google, Carlin emphasizes that "it's just a matter of price." He would have bought Amazon at a $1 trillion valuation but finds it too expensive at $3 trillion. He believes that many current tech valuations are driven by momentum rather than fundamentals. He prefers to wait for potential recessions to re-evaluate these names for value. He is happy owning "boring stocks" at attractive prices over chasing momentum stocks.
Opportunity in "Boring" Businesses
Carlin actively seeks out companies with less glamorous business models that are overlooked by the market. An example he provides is Amsterdam Commodities, a Dutch spice trading business with 200 years of history. This company has a market cap of around $800 million, pays a 6% dividend yield, and has seen its earnings grow at 8% per year over the last decade, with projections for continued growth. He considers such businesses defensive and relatively cheap, preferring them to holding cash, which he believes is certain to lose money over the long term due to inflation.
Cash vs. Active Investing
Carlin holds very little cash, as his primary activity is research and analysis to find investment opportunities. He contrasts this with Warren Buffett, who holds significant cash, explaining that Buffett's investment threshold (companies below $100 billion market cap) means he's not looking in Carlin's investment universe. Carlin believes he can still find opportunities by being more nimble.
Sector Preferences and Stock Picking
Carlin generally follows sectors with negative sentiment to find fundamental values. He notes that the chemical sector is currently experiencing this, but he's cautious about potential further downturns if a recession occurs. He also sees food as relatively cheap. He prefers picking individual stocks over broad sector bets, looking for companies that provide fundamental returns regardless of economic fluctuations.
The "Cheap for a Reason" Argument
Carlin addresses the common criticism that cheap stocks are cheap for a reason. He differentiates himself from a purely index-based value investor by stating that he analyzes businesses from a pool of potentially undervalued companies, rather than buying them all. He maintains a watch list of businesses he has followed for a decade, carefully selecting them when opportunities arise.
Management and Long-Term Fundamentals
Carlin assesses management by checking if their past statements align with current performance. He references Peter Lynch's "One Up on Wall Street," noting that fundamental principles remain constant, while other approaches "work until they don't."
Stance on ETFs and Index Funds
Carlin personally avoids ETFs and index funds, labeling them as "mindless investing." While acknowledging their low fees, he believes they offer only average returns, and he aims to outperform the average. He uses the example of Vail Resorts, where customer service issues are discussed in comments but would be missed by an ETF.
Areas of Opportunity and Watch List
Carlin is interested in sectors that thrive on volatility, such as market makers, as the VIX index has been low. He believes these businesses will benefit if current bubbles or recessions revert. He also looks at international markets, noting that the US is currently the most expensive. While he has trimmed positions in China that have doubled, he believes opportunities can still be found globally with diligent research. He finds Europe easier to understand due to his background but acknowledges the regulatory hurdles. He prefers companies with operations in the US but traded in Europe, as they can be cheaper.
Company Size and Small Caps
Carlin prefers companies with a market capitalization under $20 billion because they are often overlooked. He finds it "crazy" that large businesses with significant revenue have few analysts asking questions. He found it difficult to find value in the Russell 3000 index two years ago, suggesting that small caps' underperformance might be due to them being relatively expensive in the past.
Global Economic Outlook and Interest Rates
Carlin sees Asia as still booming, with significant growth potential that will create competition for commodities and food globally. He believes this benefits local commodity and food businesses.
Risks and Concerns
Carlin identifies significant risks in government deficits in Europe and the US, which he believes will lead to currency devaluation. He also sees risk in private equity due to borrowing costs and the need for the US government to refinance substantial debt. He likens the situation to a "house of cards" that could collapse.
Hedging Strategies
Carlin believes he is hedged through businesses like market makers, whose earnings were significantly higher during periods of volatility. He also uses dividend income from food stocks (6-8% yield) to buy assets cheaply during turmoil. He is comfortable with his strategy, stating that if nothing happens, he will still receive his dividends and wait for better value investing opportunities.
Commodities and Volatility
He follows all commodities, including coal and copper, noting significant volatility. He mentions Glenor as an example of a commodity name that was cheap but has since risen. He generally believes long-term copper players should do well.
Current Opportunities and Cyclical Sectors
Carlin finds it difficult to find opportunities without taking excessive risk. He notes that some cheap stocks still exist in Asia, but require careful management. Automotive and chemical companies are getting cheaper, but not yet cheap enough for him to invest, requiring a recession to enter these cyclical sectors.
Holding Periods and Rebalancing
Carlin's preferred holding time is "forever," as per Warren Buffett. However, he is active in rebalancing his portfolio based on fundamentals versus price. He recently trimmed his Alibaba position because, despite the stock doubling, the fundamentals hadn't improved, and the growth was reliant on AI promises. He views China's risks as unchanged.
Growth and Tech Exposure
Carlin does not own growth or AI-exposed companies, having previously owned Alibaba before its AI focus. He believes the essence of value investing is not outperforming but focusing on performing and achieving personal financial goals through compounding dividends and fundamental analysis.
Areas of Caution and "No-Go" Areas
Carlin is particularly cautious about international investing risks, especially in commodities like copper, where political changes in countries like Chile can lead to significant losses. He mentions that ETFs might be a way to play commodities if individual stock risks are too high. He highlights the risk of governments confiscating assets, as has happened in Indonesia with mines.
Advice to Investors
Carlin's primary advice is to check the risk of one's current portfolio and its potential impact on their life. He warns of potential 50-60% losses in tech names if AI doesn't meet expectations or if Chinese AI proves superior and cheaper. He suggests hedging, such as buying a put on the S&P 500 for a small portion of the portfolio, to sleep better at night.
AI's Impact on "Boring" Companies
Carlin believes that while AI will change the world and is a remarkable tool, the real winners will be companies that use AI, not necessarily those building the infrastructure. He anticipates that intense competition will drive down prices, benefiting the customer. He cites Jeff Bezos's view that customers will win due to immense competition in AI, making it unlikely to lead to massive profits for many investors.
Conclusion
Sven Carlin advocates for a disciplined value investing approach focused on risk avoidance and fundamental returns. He believes that while momentum stocks have performed well, their valuations are stretched, creating significant risk. He actively seeks out overlooked, "boring" businesses with strong fundamentals, attractive dividend yields, and defensive qualities. He emphasizes the importance of price discipline, continuous research, and hedging against potential market downturns, even if it means missing out on some of the speculative gains seen in high-growth sectors.
AI summaries can miss context or contain errors. Check important details against the original video.