Key Concepts
- Budget Impact on Investors: The primary focus of the summary is to analyze the effects of the recent budget on investment strategies and returns.
- Market Reaction: The immediate response of financial markets (gilts, sterling, FTSE 250) to the budget announcement and pre-announcement leaks.
- ISAs (Individual Savings Accounts): Changes to ISA allowances, particularly the distinction between cash and stocks and shares ISAs, and their implications for savers.
- Pensions: The introduction of a cap on salary sacrifice for pensions and its impact on tax-free contributions.
- Dividend Tax: Increases in dividend tax rates for income earned outside of ISAs and pensions.
- Stamp Duty for New Listings: An exemption for newly listed UK companies to encourage stock market listings.
- Property Income Tax (Landlords): Increases in tax rates for rental property income.
- Mansion Tax: A new tax on high-value properties.
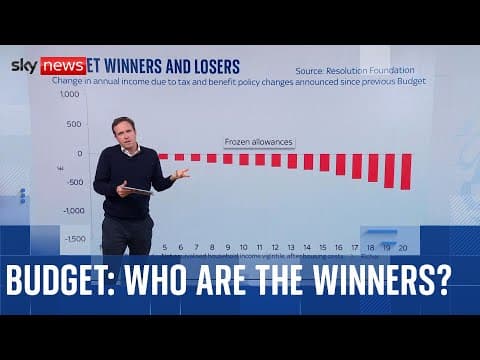
- Fiscal Drag: The effect of frozen tax thresholds on individuals' tax liabilities as wages rise with inflation.
- OBR Forecasts: Analysis of the Office for Budget Responsibility's projections for productivity, economic growth, inflation, and interest rates.
- Productivity Crisis: The persistent issue of low productivity growth in the UK and its contributing factors.
- Debt and Borrowing: Government debt levels, public sector net borrowing, and the cost of servicing national debt.
- Investment Opportunities: Potential investment avenues such as gilts, UK investment grade corporate bonds, and the attractiveness of fixed income.
- Diversification and Tax Efficiency: The importance of diversified, tax-efficient investing strategies in the current economic climate.
- Geopolitical Risks: The potential impact of global events like the Russia-Ukraine war and China-Taiwan tensions on investment portfolios.
Budget Summary and Investor Impact
This summary details the key announcements from the recent budget and their implications for investors, focusing on market reactions, specific policy changes, and economic forecasts.
Market Reaction to the Budget
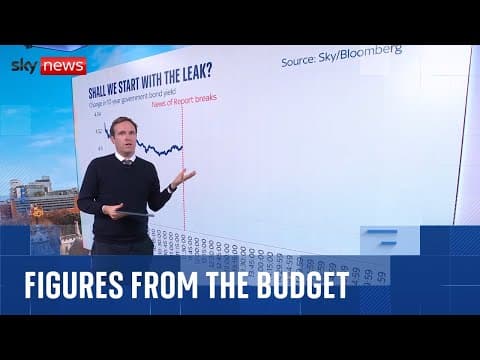
The budget's release was preceded by an OBR leak, which significantly influenced market movements.
- Gilts: Initially rallied on the OBR leak due to expectations of lower new gilt issuance. They then fell as the Chancellor began speaking but recovered towards the end of the day. This pattern was observed across various gilt maturities, including the 73-year bond.
- Sterling: Showed a similar intraday pattern: a rally following the OBR leak, a dip during the initial part of the Chancellor's speech, and a subsequent rally.
- FTSE 250: Chosen as a barometer for the UK economy due to its focus on domestic stocks, it mirrored the pattern of a spike from the leak, a fall, and then a rally.
The overall market reaction suggests the budget is not expected to be a major catalyst for significant economic shifts, indicating a "steady as she goes" approach.
Key Policy Changes and Their Investor Impact
1. ISAs (Individual Savings Accounts)
- Overall Allowance: The annual ISA allowance remains at £20,000 from April 2027. However, in real terms, this represents a decrease, meaning less tax-free saving is possible due to fiscal drag.
- Cash ISA Limit: A new limit of £12,000 per year is imposed on cash ISAs from April 2027.
- Stocks and Shares ISA Requirement: To utilize the full £20,000 allowance, at least £8,000 must be invested in a stocks and shares ISA.
- Rationale: The government aims to encourage investment in productive assets (stocks, bonds) rather than cash, which is seen as less beneficial for economic growth and capital markets.
- Exemption: Individuals aged 66 and over retain the full £20,000 allowance for cash ISAs, acknowledging lower risk tolerance in retirement.
- Investor Strategy: Those under 66 who prefer holding most of their ISA in cash will need to adjust their strategy. An alternative is to hold a money market fund within a stocks and shares ISA, which offers similar risk and return profiles to a cash ISA.
2. Pensions
- Salary Sacrifice Cap: From April 2029, a £2,000 annual cap will be introduced for salary sacrifice contributions to pensions that are free of National Insurance (NI). Contributions exceeding this cap will attract both employee and employer NI.
- Example: For an individual earning £45,000 contributing 5% (£2,250) via salary sacrifice, the £250 above the £2,000 cap would incur approximately £30 in extra employee NI and a similar amount for the employer.
- Revenue Generation: The OBR estimates this change will generate around £4.7 billion over the period 2029-2030.
- Tax-Free Pension Lump Sum: The 25% tax-free lump sum at retirement remains unchanged, with a cap of £268,275.
- Investor Strategy: Individuals utilizing large salary sacrifice contributions for tax optimization may find this less generous. Reviewing contributions above the £2,000 cap and considering ISAs and other tax wrappers is advised.
3. Dividend Tax
- Rate Increase: From April 2026, dividend tax rates will increase by two percentage points for income earned outside of ISAs and SIPs.
- Basic Rate: 8.75% to 10.75%
- Higher Rate: 33.75% to 35.75%
- Additional Rate: Remains unchanged at just under 40%.
- Dividend Allowance: The tax-free dividend allowance has already been reduced to £500.
- Revenue Generation: The OBR forecasts these increases to raise approximately £1.2 billion per year from 2027-2028.
- Impact: This makes holding dividend-paying shares and funds outside tax wrappers less tax-efficient, particularly for those receiving large lump sums from liquidity events or inheritances that cannot be fully sheltered within ISAs and SIPs in a single tax year.
4. Stamp Duty for New Listings
- IPO Stamp Duty Holiday: Newly listed UK companies will be exempt from stamp duty for three years after listing on the London Stock Exchange.
- Objective: To make the UK stock market more competitive with international exchanges (New York, Europe) and encourage more companies to list in the UK.
- Rationale: A lack of new listings can lead to the eventual decline of a stock market.
- Critique: While a positive step, the speaker would have preferred a complete abolition or significant reduction of stamp duty for a more transformative impact.
5. Property Income Tax (Landlords)
- Rate Increase: From April 2027, property income tax rates will increase by two percentage points:
- Basic Rate: 20% to 22%
- Higher Rate: 40% to 42%
- Additional Rate: 45% to 47%
- Revenue Generation: The OBR estimates this will generate around £500 million per year.
- Mansion Tax: A new tax applies to houses worth over £2 million, with a maximum annual charge of £7,500. This primarily affects London and the South East.
- Positive for Landlords: The anticipated National Insurance charge on rental income did not materialize.
- Overall Outlook for Landlords: The message is described as "bleak" due to cumulative reforms (stamp duty on second homes, reduced capital gains allowances, tighter regulations) making the sector less attractive. Many landlords are reportedly exiting the market, which could lead to reduced rental property supply and increased rental costs.
OBR Forecasts and Economic Outlook
The OBR forecasts paint a concerning picture for the UK economy, particularly regarding productivity.
- Productivity Growth: Forecast for medium-term productivity growth has been cut from 1.3% to 1.0% per year. This compounds significantly over time, impacting overall economic potential.
- Potential Economic Growth: Fallen from 1.8% to 1.5% per year.
- Reasons for Productivity Crisis:
- Slower global trade growth.
- Brexit's permanent reduction in UK trade volumes and increased friction.
- Economic shift towards less productive sectors like health and social care.
- Fading impact of past technological and financial service booms.
- Aging population and restricted immigration.
- Energy transition and climate risks.
- AI Impact: The OBR anticipates AI will add approximately 0.2 percentage points to annual productivity growth by 2030, but this is not expected to be transformative in the short term due to initial investment and disruption.
- GDP Growth: Expected to average around 1.5% per year, with an upgrade to 1.5% for 2025 but lower than previously assumed thereafter due to productivity downgrades.
- Inflation: Forecast to remain higher for longer, with CPI around 3.5% in 2025, falling to 2.5% in 2026, and reaching the Bank of England's 2% target by 2027.
- Interest Rates: Bank Rate is expected to drift down slowly to around 3.6% by the end of 2026. Zero interest rates are not anticipated.
- Government Borrowing Costs: 10-year gilt yields are expected to average around 5.1% over the forecast period, leading to some of the highest government borrowing costs in the G7.
Debt and Borrowing
- Public Sector Net Borrowing (Deficit): Expected to fall from 4.5% of GDP in 2025-2026 to 1.9% of GDP by 2030-2031, indicating a shrinking deficit.
- Debt to GDP Ratio: Forecast to peak at 97% of GDP in 2028-2029 and then gradually fall. This high level is attributed to past crises (global financial crisis, COVID-19).
- Debt Servicing Costs: The monetary amount paid in interest on government debt is projected to increase from £114 billion in 2025-2026 to £140 billion per year by 2031. This represents money not spent on public services.
Investment Opportunities and Strategies
- Fixed Income: High yields on government bonds (gilts) are seen as an opportunity. UK investment grade corporate bonds are also suggested, offering a credit spread over the risk-free rate, though with added risk.
- Tax Wrappers: The increasing dividend tax rates and frozen income tax thresholds make ISAs and pensions more valuable for tax-efficient investing.
- Diversification: Essential due to the risk of sticky inflation eroding cash flow values.
- Investor Profile: The budget is seen as pushing savers towards investments, squeezing landlords, and increasing tax burdens. Boring, diversified, tax-efficient investing is expected to thrive.
Q&A Highlights
- HIC and TRIG Merger: A £5.3 billion merger of infrastructure investment trusts is seen as positive for economies of scale and potentially larger projects. The speaker emphasizes the need for policy continuity for infrastructure investors.
- Clean Energy Investment: The speaker notes that renewable energy investment trusts have seen significant price drops, highlighting the impact of policy uncertainty, particularly with potential government changes.
- Offshore Bonds: The speaker has previously covered offshore bonds in member-only videos, noting their relevance for high-net-worth individuals who have exhausted ISA and SIP allowances.
- UK Housing Market: Real UK house prices have stagnated for 20 years. Wage growth, linked to productivity, is a key driver of property prices. The outlook is poor with low productivity growth.
- ETF Wind-Down: A common threshold for ETF wind-down is around £30 million in Assets Under Management (AUM), as this level may not generate sufficient income to cover operational costs.
- Portfolio Allocation: The speaker's core portfolio is 60% global equity and 40% money market funds, with an additional 10% in a "fun" portfolio of riskier assets.
- Work Pension Transfer: For cash transfers into a SIP, the speaker personally prefers to drip-feed investments due to caution, though statistics suggest investing immediately is often more beneficial.
- Workplace Pension Divestment: A 30-year-old's workplace pension divesting 10% into long-dated gilts is likely a hedging strategy, though the speaker notes the volatility of long-dated gilts.
- Geopolitical Risk and ETFs: The speaker advises against making large tilts based on geopolitical risks (e.g., Russia-Ukraine war, China-Taiwan tensions) due to unpredictability. Diversification and humility are key, with smaller tilts in a "fun" portfolio being more appropriate. Safe assets like gilts, money market funds, or gold are recommended in scenarios of extreme geopolitical instability.
Conclusion
The budget is characterized as generally favorable for investors, particularly those who engage in diversified, tax-efficient strategies. Key changes include nudging savers towards stocks and shares ISAs, increasing dividend taxes outside wrappers, and making property investment less attractive. The economic outlook is tempered by persistent low productivity growth and high government debt, but attractive yields in fixed income present opportunities. The speaker emphasizes the importance of adapting long-term investment plans to these policy shifts.
AI summaries can miss context or contain errors. Check important details against the original video.