Key Concepts
- Cash Holdings: The amount of cash a company keeps on hand.
- Motives for Holding Cash: Reasons why companies hold cash, including operational needs, shock absorption, life cycle stage, and managerial power.
- Balance Sheet: A financial statement that reports a company's assets, liabilities, and equity.
- Operating Investments: Assets directly used in a company's core business operations.
- Non-Operating Assets: Investments in other companies or assets not directly related to core operations.
- Marketable Securities: Short-term, liquid investments that can be easily converted to cash.
- Working Capital: The difference between a company's current assets and current liabilities, used to fund day-to-day operations.
- Shock Absorber: Cash held to mitigate the impact of unexpected financial difficulties.
- Cash Burn Ratio: A metric used to assess how long a company can continue operating with its current cash reserves.
- Growth Option: Cash used to fund future growth opportunities.
- Youth Serum: Cash used by mature companies to attempt to regain growth and vitality.
- Liquidation: The process of selling off a company's assets to pay off debts and distribute remaining funds.
- Corporate Governance: The system of rules, practices, and processes by which a company is directed and controlled.
- Bitcoin: A decentralized digital currency and payment system.
- Blockchain: A distributed, immutable ledger that records transactions across many computers.
- Valuation vs. Pricing: Valuation involves determining an asset's intrinsic worth, while pricing is determined by market forces of supply and demand.
- Asset: An item of economic value that a company owns or controls with the expectation that it will provide future benefit.
- Commodity: A raw material or primary agricultural product that can be bought and sold.
- Currency: A medium of exchange for goods and services.
- Collectible: An item that is sought after by collectors and whose value is driven by scarcity and desirability.
- Micro Strategy: A technology company that has significantly invested in Bitcoin.
- Bitcoin Maximalist: An individual who believes Bitcoin is the only cryptocurrency worth investing in.
- Meme Stock: A stock that gains popularity through social media and online communities, often detached from its underlying business fundamentals.
Cash Holdings in Companies
Motives for Holding Cash
The speaker outlines several key reasons why companies hold cash, moving beyond the basic operational needs often taught in introductory finance.
- Operational Lubricant (Working Capital): Historically, cash was essential for day-to-day operations, such as providing change in retail. A rule of thumb, like McKinsey's suggestion of 2% of revenues, was used, though this is now considered outdated.
- Shock Absorber: Cash acts as a buffer against unforeseen events like recessions, commodity price drops, or other financial shocks that could destabilize a company.
- Life Cycle Stages:
- Startup (Pre-revenue): Cash is needed to cover salaries, R&D, and reinvestment.
- Young Growth Company (Money-losing): Cash is a "life preserver" to sustain operations while growing revenues. The "cash burn ratio" was used to assess risk.
- High Growth Firm: Cash acts as a "scalar" to facilitate expansion from a small to a larger company, even with low profits.
- Mature Growth: Cash is used to explore new growth avenues, termed "growth options."
- Mature Firm: Cash is seen as a "youth serum" to attempt to revitalize the company, though often unsuccessfully.
- Decline: Cash is used to manage an orderly liquidation, paying off debts and avoiding fire sales.
- Managerial Power and Empire Building: The speaker posits that managers, if left unchecked, tend to hold onto cash because it grants them power, attracts attention from bankers and consultants, and enables them to pursue acquisitions and build empires.
Cash Balances in Public Companies
Data presented indicates substantial cash holdings globally:
- US Companies: Hold approximately $2.4 trillion in cash, representing about 9% of their total book value.
- Global Companies: Hold $11.4 trillion in cash, accounting for nearly 11% of their total book value.
Sectoral and Regional Cash Holdings
Cash balances vary significantly across industries and geographic regions:
- By Sector (Book Value Basis):
- Highest: Technology (around 19% of book value), attributed to higher uncertainty.
- Lowest: Real Estate and Utilities, which are more stable businesses.
- By Sector (Market Value Basis): Technology companies drop significantly in cash holding rankings when considering market value, as their market capitalization often far exceeds their book value.
- By Region:
- Highest: China, Eastern Europe.
- Reasons for Higher Balances: Uncertainty (e.g., Latin America) and corporate governance issues (e.g., Eastern Europe and Russia), where managers may hoard cash if not pressured to return it to shareholders.
Cash Holdings by Corporate Age
- Younger firms, in aggregate, tend to hold more cash as a percentage of both book value and firm value compared to older firms. However, the pattern is not consistently discernible across all age deciles.
Bitcoin: A Currency or Collectible?
Origins and Design Philosophy
Bitcoin emerged in November 2008, during a major financial crisis, with a design philosophy rooted in distrust of institutions.
- Satoshi Nakamoto: The pseudonymous creator of Bitcoin.
- Blockchain Technology: The core innovation, enabling peer-to-peer transaction verification without relying on central authorities.
- "Currency Designed by the Paranoid for the Paranoid": This description highlights Bitcoin's emphasis on decentralization and self-sovereignty in a world perceived as untrustworthy.
Price Performance and Valuation Challenges
Bitcoin has experienced dramatic price increases, particularly in recent years, leading to questions about its valuation.
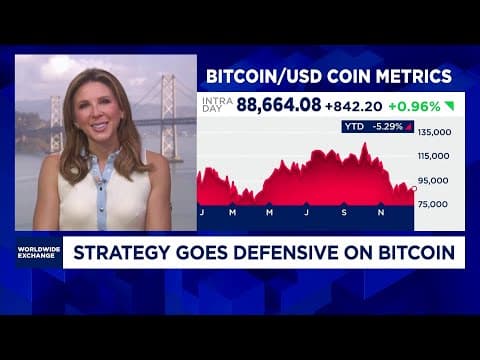
- Price Surge: From under $400 to nearly $110,000 by June 2025.
- Inability to Value: The speaker argues that Bitcoin cannot be valued in the traditional sense because it doesn't fit the definition of an "asset" with cash flows.
Categorizing Bitcoin: Asset, Commodity, Currency, or Collectible?
The speaker categorizes investments into four groups to understand Bitcoin's nature:
- Assets: Have cash flows (e.g., businesses, stocks, bonds). Can be valued.
- Commodities: Primarily priced by supply and demand (e.g., oil). Difficult to value.
- Currencies: Cannot be valued but can be priced based on their utility as a medium of exchange and store of value (e.g., USD).
- Collectibles: Cannot be valued; priced by supply and demand, driven by scarcity and desirability (e.g., gold, Picassos).
Bitcoin is argued to be either a currency or a collectible.
- As a Currency: Bitcoin has seen limited success, used for some illegal transactions and in countries with unstable fiat currencies (e.g., El Salvador), but has not achieved widespread adoption for everyday purchases.
- As a Collectible: Bitcoin is scarce (limited to 21 million units). However, unlike traditional collectibles like gold, it has historically behaved more like a risky stock during crises rather than a stable store of value.
The debate over whether Bitcoin is "cheap" or "expensive" is deemed a waste of time, as its price is driven by perception and market sentiment rather than intrinsic value.
The Micro Strategy Case and the Push for Corporate Bitcoin Adoption
Micro Strategy: A Bitcoin-Driven Success Story
Micro Strategy, a software company, has seen its market capitalization explode due to its significant Bitcoin holdings, overshadowing its core business performance.
- Stock Performance: Lagged the S&P 500 until recent years, when its stock price became highly correlated with Bitcoin's price.
- Revenue vs. Market Cap: Micro Strategy's revenues and operating income have declined over the past decade, while its market cap has surged from under $1 billion to over $90 billion.
- CEO's Role: CEO Michael Saylor is a prominent Bitcoin advocate who has actively raised equity to purchase more Bitcoin, effectively transforming the company into a "Bitcoin spa" where investors trust his trading acumen.
Arguments Against General Corporate Bitcoin Adoption
The speaker strongly advises against most companies adopting Bitcoin as a treasury asset, citing five key reasons:
- Fails as a Shock Absorber: Bitcoin's high volatility makes it unsuitable to replace cash as a stable buffer against financial downturns.
- Distracts from Core Business: Investing in Bitcoin can dilute a company's narrative and distract investors from its operating business story. The price movements of Bitcoin can drown out the company's actual performance.
- Managerial Trading Incompetence: Managers historically perform poorly as traders, often buying high and selling low. Entrusting them with Bitcoin trading is risky.
- Shareholder Preference for Direct Investment: If a company's shareholders believe in Bitcoin, they would likely prefer to receive cash dividends or distributions to invest in Bitcoin themselves, allowing for personal choice in asset allocation.
- License for Abuse and Scandals: Allowing managers to invest company cash in Bitcoin opens the door to potential abuse, lack of transparency, and the disappearance of funds, leading to corporate governance scandals.
Carve-Outs: When Corporate Bitcoin Adoption Might Make Sense
Despite the general caution, the speaker identifies four specific scenarios where companies might consider holding Bitcoin:
- The "Bitcoin Maximalist" CEO/CFO (Micro Strategy Model): Companies with a CEO or CFO who deeply understands Bitcoin, can gauge its direction, and effectively "time the market." Investors in such companies are essentially betting on the leadership's ability to trade Bitcoin successfully, similar to investing in Berkshire Hathaway based on Warren Buffett's investment prowess.
- Business Requirement for Bitcoin: Companies whose core business operations inherently involve Bitcoin transactions (e.g., PayPal, Coinbase). The Bitcoin balance should be proportionate to these operational needs.
- The "Bitcoin Escape Artist" (Currency Instability): Companies operating in countries with highly unstable domestic currencies (e.g., Mercado Libre in Argentina). Bitcoin can serve as a more stable alternative to preserve value.
- The "Meme Company" (Broken Operating Business): Companies whose core operating businesses have failed but have become "meme stocks" (e.g., AMC, GameStop). These companies, having already abandoned their original business models, might pivot to becoming full Bitcoin plays.
Guardrails for Corporate Bitcoin Adoption
For companies that do decide to adopt Bitcoin, strict guardrails are essential:
- Shareholder Buy-in: Explicit approval from shareholders is required to signal a commitment to becoming a "Bitcoin player."
- Transparency: Full transparency regarding Bitcoin transactions, including purchase and sale timings and holdings, is crucial. Companies cannot hide behind security concerns to withhold information.
- Clear Mark-to-Market Accounting: Standardized accounting rules for marking Bitcoin holdings to market value and clear disclosure in financial statements are necessary for investors to track these assets.
Implications for Bitcoin Advocates and the Market
The push for institutional adoption of Bitcoin by advocates has significant implications:
- Shifting Investor Base: Institutional investors and companies will bring a different risk profile and trading behavior compared to historical Bitcoin traders, potentially altering market dynamics.
- Volatility Risk: While Bitcoin is performing well now, institutions and companies, being prone to herd behavior, could rapidly exit their positions during downturns, exacerbating Bitcoin's volatility.
- Loss of Differentiated Behavior: As Bitcoin becomes more integrated into traditional finance, it may lose its characteristic of moving independently from stocks and bonds, similar to how real estate's behavior changed in the 1980s.
The speaker advises true Bitcoin believers to be cautious about aggressively pushing for establishment adoption, as it may fundamentally change the nature of the asset.
Conclusion
The session distinguishes between the general question of whether companies should hold cash and the specific, and often ill-advised, proposition of companies investing their cash in Bitcoin. While cash serves vital functions as a lubricant and shock absorber, Bitcoin's volatility and speculative nature make it unsuitable for most corporate treasury strategies. However, specific niche cases, such as companies with Bitcoin-savvy leadership, those with direct business needs for Bitcoin, or those in countries with unstable currencies, might find limited justification for holding Bitcoin, provided stringent transparency and governance measures are in place. The broader implications of institutional adoption on Bitcoin's market characteristics and volatility are also highlighted as a critical consideration.
AI summaries can miss context or contain errors. Check important details against the original video.