Double Diagonal Options Strategy: A Detailed Breakdown
Key Concepts:
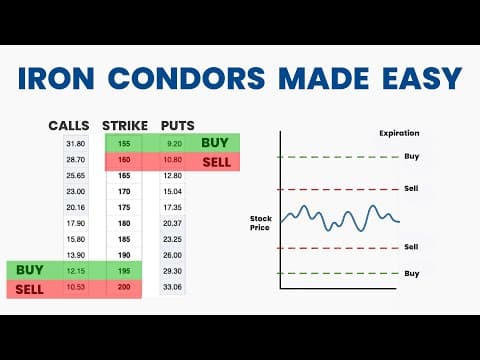
- Double Diagonal: An options strategy involving selling out-of-the-money calls and puts with a near-term expiration, and simultaneously buying further out-of-the-money calls and puts with a later expiration date.
- Delta: A measure of an option's sensitivity to changes in the underlying asset's price; also correlated to the probability of the option expiring in-the-money.
- Bid-Ask Spread: The difference between the highest price a buyer is willing to pay (bid) and the lowest price a seller is willing to accept (ask) for an option.
- Flat Price Chart: A chart showing minimal price fluctuation in the underlying asset over a period of time.
- Expiration Date: The date on which an option contract ceases to exist.
- In-the-Money (ITM): An option with intrinsic value; a call option is ITM when the underlying asset's price is above the strike price, and a put option is ITM when the underlying asset's price is below the strike price.
- Out-of-the-Money (OTM): An option without intrinsic value.
I. Strategy Prerequisites & Setup
The core of this strategy revolves around identifying and exploiting sideways price movement in an underlying asset. Three key criteria must be met before initiating a trade:
- Flat Price Chart: The underlying asset (stock, ETF, or index) must exhibit a relatively stable price history. The example used is TLT (iShares 20+ Year Treasury Bond ETF), which traded between $82 and $109, primarily within the $87-$100 range for the preceding two years, closing at $87.57 on January 1st, 2025.
- Monthly Expirations: The options chain for the asset must offer at least monthly expiration dates. Weekly expirations are preferable, but quarterly expirations are unsuitable. TLT was confirmed to have monthly expirations.
- Tight Bid-Ask Spreads: The options chain should demonstrate narrow bid-ask spreads (typically 1-3 cents), indicating high liquidity and fair pricing. TLT’s options chain met this requirement.
II. Trade Implementation – Step-by-Step Process
The strategy is designed to be executed 12 times per year, starting on the third Friday of each month. This date was chosen due to the consistent availability of monthly option expirations.
- Initial Trade (Third Friday of the Month):
- Identify the stock price on the third Friday (e.g., TLT closed at $87.19 on January 17th, 2025).
- Determine strike prices with a delta below 20 on both the call and put sides. For TLT, this meant selling the 91 call (delta 18.23) and the 83 put.
- Sell 10 contracts each of the selected call and put options.
- Second Leg (Approximately Two Months Later):
- Identify options expiring approximately two months later (e.g., February 21st trade rolls to March 21st expiration).
- Buy call options five points higher than the sold call (e.g., buy the 96 call).
- Buy put options five points lower than the sold put (e.g., buy the 78 put).
- Buy 10 contracts each of the selected call and put options.
- The Double Diagonal: This combination of selling near-term OTM options and buying further-dated OTM options creates the “double diagonal” spread.
III. Rationale Behind Delta Selection (<20)
The selection of options with a delta below 20 is crucial. Delta represents the predicted price change of an option for every $1 change in the underlying asset. More importantly, delta is highly correlated with the probability of the option expiring in-the-money.
- A 20 delta call option has approximately a 20% chance of expiring in-the-money (stock price above strike price). This implies an 80% chance of expiring worthless.
- A 20 delta put option has approximately a 20% chance of expiring in-the-money (stock price below strike price). This implies an 80% chance of expiring worthless.
The strategy aims to profit from the high probability of these options expiring worthless, collecting the premium as profit.
IV. Cash Flow & Risk Management
- Initial Cash Flow: The initial trade generates positive cash flow from selling the near-term options. In the first example, $360 was received from selling the 91 calls and $340 from selling the 83 puts, netting $240.
- Capital Requirement: The broker requires approximately $4,760 in the account to cover the worst-case scenario.
- Managing Potential Assignment: If the underlying asset’s price moves significantly and threatens to move an option in-the-money before expiration, the option may be assigned. In the April trade example, the 88 put became in-the-money, requiring the trader to buy it back to avoid assignment, incurring a cost of $470. However, the corresponding long put (78) had increased in value, offsetting the loss.
V. 12-Month Performance Example (2025)
The video presented a 12-month example using TLT, demonstrating the strategy’s performance.
- Consistent Profitability: In most months, TLT’s price remained within the range defined by the sold call and put options, allowing both to expire worthless, generating profit.
- April Anomaly: The April trade was the only instance where one of the short options (the 88 put) did not expire worthless, requiring a buyback. However, the long put (78) increased in value, mitigating the loss.
- Annual Return: The strategy generated a total profit of $3,645 over the 12-month period, representing a 77.5% return on capital. It was noted that results will vary year to year.
VI. Repeating the Trade & Annual Analysis
The strategy is designed to be repeated monthly, rolling the trade forward at each expiration. Analyzing the profit and loss across all trades in a year provides a comprehensive assessment of the strategy’s effectiveness.
Notable Quote:
“...the logic behind the strategy is strong, which is how we can get such an extraordinary return like we did in 2025.” – Speaker, emphasizing the underlying principles of the strategy.
Conclusion:
The double diagonal options strategy, when applied to flat price charts, offers a potentially profitable approach for options traders. Its success hinges on identifying suitable underlying assets, carefully selecting strike prices based on delta, and consistently implementing the defined process. While not without risk, the strategy’s structure allows for a high probability of profit if the underlying asset remains within a defined range. Disciplined execution and ongoing monitoring are crucial for maximizing returns and mitigating potential losses.
AI summaries can miss context or contain errors. Check important details against the original video.