Key Concepts
- Exchange Rate Intervention: Government actions to influence the value of its currency in foreign exchange markets.
- Exchange Stabilization Fund (ESF): An emergency fund managed by the U.S. Treasury used for international financial stability.
- Currency Swap Framework: An agreement between central banks to exchange currencies, providing liquidity.
- Fiscal Discipline: Prudent management of government spending and revenue to control deficits and debt.
- Deregulation: The reduction or elimination of government regulations on businesses and markets.
- Dollarization: Adopting the U.S. dollar as the official currency of a country.
- Speculative Attacks: Market actions aimed at devaluing a currency, often by short-selling it.
- Geopolitics: The influence of political and economic geography on international relations.
- Conditionality: Requirements attached to financial assistance, often from the IMF, to ensure policy reforms.
Argentina's Currency Crisis and U.S. Intervention
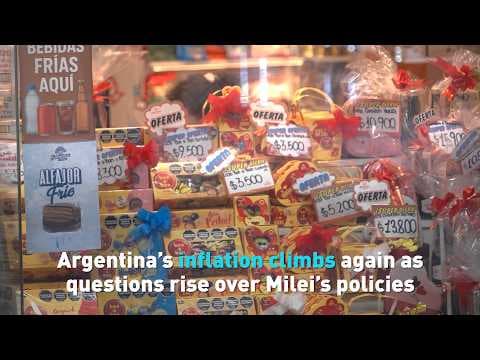
Argentina is facing a severe economic crisis, characterized by a rapid depletion of U.S. dollar reserves to defend the peso and maintain an unsustainable exchange rate. In just seven trading sessions, the Treasury sold $1.8 billion dollars. Interest rates on short-term debt have surged past 87%, and the central bank's reserves are dwindling. The government is employing a multi-pronged strategy, including interventions in spot and futures markets, reinstating selective foreign-exchange controls, and clinging to a currency band that is increasingly viewed as unrealistic by markets.
President Javier Milei is committed to maintaining the peso's value until the midterm elections on October 26th, where half of Congress is up for election. However, the extensive dollar sales highlight the unsustainability of the current exchange rate. While a U.S. Treasury pledge of support last month provided temporary market calm, it did not reverse the peso's slump.
Escalated U.S. Involvement
The U.S. has significantly increased its involvement in Argentina's economic situation. On Thursday of the current week, Treasury Secretary Scott Bessent announced that the U.S. Exchange Stabilization Fund (ESF) had directly purchased Argentine pesos. This is a rare move, with the ESF having intervened directly only four times in the past thirty years. Its most recent high-profile intervention was in 2011 as part of a G7 effort to control a spike in the yen following the Fukushima earthquake. The ESF is also known for its $20 billion loan to Mexico in 1994 to support its currency after a collapse, of which Mexico drew down $12 billion and repaid with a profit.
Furthermore, Bessent finalized a $20 billion currency swap framework with Argentina's central bank, describing Milei's reform program as "of systemic importance."
Bipartisan Backlash in Washington
These interventions have sparked bipartisan criticism in Washington. Republicans question whether the actions align with an "America First" agenda, suggesting a potential shift to an "America First—unless Argentina needs twenty billion dollars and a hug" policy. Democrats are investigating potential involvement of hedge funds associated with Scott Bessent and whether taxpayer dollars should support a foreign president whose policies might negatively impact American farmers.
President Milei's Reform Agenda and Early Successes
Javier Milei assumed office in December 2023 with a promise to dismantle decades of Peronist interventionism and restore Argentina's economic credibility. His initial actions were drastic:
- Budget Balancing: He balanced the budget within a single quarter, reducing the deficit from 5% of GDP to zero.
- Inflation Reduction: Annual inflation, which had exceeded 200%, began to fall sharply, reaching approximately 2% monthly by mid-2025. The IMF publicly commended his fiscal discipline.
- Housing Market Deregulation: In his first month, Milei repealed rent control laws. This led to an immediate surge in rental listings (180%) on real estate platforms, a fall in real rents, and a return of long-term leases. The Cato Institute described this as a "textbook case" of deregulation benefiting both tenants and landlords.
- Housing Market Recovery: High inflation had previously halted home sales due to the impossibility of long-term borrowing. With falling inflation, mortgages have become available, and housing transactions have resumed.
Milei's economic philosophy is rooted in free-market orthodoxy, contrasting sharply with his predecessors' populist statism. His policy agenda, more aligned with Milton Friedman than MAGA, included slashing tariffs, scrapping export taxes, and initiating privatization of state assets. For a country long plagued by inflation, capital controls, and fiscal mismanagement, Milei's early months offered a rare period of coherent reform.
Challenges to Milei's Reforms
Despite initial successes, Milei's political standing has weakened due to several factors:
- Scandals: Three major scandals have eroded his credibility:
- Involvement in a meme coin scheme.
- Accusations against his sister and chief of staff for alleged kickbacks related to pharmaceutical sales.
- Resignation of his lead congressional candidate, José Luis Espert, who admitted to receiving payments from a businessman under drug trafficking investigation.
- Political Defeat: Milei's coalition suffered a significant defeat in Buenos Aires Province in the previous month's elections, a region representing nearly 40% of Argentina's electorate. While the region leans left, the scale of the loss exceeded expectations, signaling voter fatigue with austerity and growing concern over corruption.
- Strained Alliances: Milei's alliances with centrist opposition parties have deteriorated. Congress has already overturned one of his vetoes on a spending bill and is preparing to challenge three more. A new bill in the lower house aims to limit his ability to govern by decree, further restricting his reform capacity. The Economist has questioned Milei's governability, noting the erosion of his political strength.
With the upcoming midterm elections, Milei faces a crucial test. Even a modest gain in congressional seats could help him block adverse legislation and protect his reform agenda. However, a poor electoral outcome could jeopardize his ability to govern and the sustainability of his economic program.
Geopolitical Considerations and U.S. Strategy
Treasury Secretary Scott Bessent's statement of U.S. readiness to support Argentina has calmed markets but also raised questions in Washington. The U.S. bailout may extend beyond economic considerations, reflecting growing concern over China's influence in South America. Argentina has an $18 billion swap line with the People's Bank of China, and Beijing is expanding its trade ties in the region. Bessent has stated that Milei is "committed to getting China out of Argentina."
The Trump administration has reportedly urged Argentina to reinstate export taxes on farm products. This move would benefit U.S. agricultural interests but undermine Milei's free-market agenda and hinder Argentina's ability to generate foreign exchange for debt repayment. Critics argue that blaming countries like Argentina and Brazil for selling agricultural produce to China, thereby competing with U.S. producers, is unreasonable, especially given the U.S. initiated a trade war with its own agricultural sector's key customers.
Scott Bessent maintains that this is not a bailout and believes the peso is undervalued. However, most economists disagree, arguing the currency is overvalued, harming Argentina's competitiveness. Evidence of overvaluation includes Argentinians making shopping trips to Chile, where the peso's purchasing power makes foreign electronics cheaper than domestic staples like rice.
The Atlantic and FT Alphaville suggest the bailout has significant geopolitical dimensions, with the U.S. aiming to counter Beijing's growing influence in South America by backing Milei. This strategy carries risks; if Milei fails, the U.S. will have invested billions in a currency and presidency that could not endure.
Brad Setser of The Council on Foreign Relations views the intervention as a gamble that Argentina's problems are primarily political and that Milei can achieve an unexpected electoral victory. For Scott Bessent's bet to succeed, many factors must align favorably, which has historically been challenging for Argentina.
Historical Precedents and Argentina's Economic Cycle
Argentina's economic history is marked by repeated cycles of currency crises and failed attempts to maintain artificially high exchange rates. The country has defaulted nine times since its independence in 1816 and is currently the largest borrower from the IMF, accounting for over a third of its global lending portfolio.
Historical examples of failed currency defense include:
- European Monetary System (1992): The UK was forced to exit the ERM under speculative pressure.
- Thailand (1997): The defense of a fixed exchange rate against the U.S. dollar depleted reserves, leading to the abandonment of the peg and a major financial crisis.
- Mexico (1994): The peso crisis resulted in a $50 billion bailout coordinated by the U.S. and the IMF.
These cases share a common pattern: an artificially strong currency, depletion of reserves in its defense, and a subsequent devaluation that shocks markets and citizens.
The IMF's current program with Argentina includes a $20 billion Extended Fund Facility, with $12 billion already disbursed. However, reserve accumulation targets have been missed, and the peso remains overvalued. The U.S. bailout via the ESF appears to lack the conditionality that aided Mexico's recovery. As Brad Setser noted, "Unconditional bailouts incentivize bad policy."
Without a move towards greater exchange rate flexibility and a sustainable strategy for rebuilding reserves, Argentina risks repeating past mistakes. While the peso band might hold until the election, historical patterns suggest its long-term sustainability is unlikely.
The Current Situation: A Familiar Pattern
Argentina's economic history is replete with failed experiments, including currency pegs, populist spending, and reform programs that succumbed to political pressure. The current situation bears a worrying resemblance to these past failures. Milei's initial successes are now overshadowed by mounting risks: a currency under pressure, dwindling reserves, and a reform agenda facing opposition from Congress and the electorate.
The IMF has already made concessions to keep its program with Argentina active. The U.S. Treasury is deploying nearly all its liquid reserves to support a bailout lacking enforceable conditions. The peso remains overvalued, reserve targets have been missed, and the political coalition necessary for sustained reform is weakening.
Argentina's "fixed-but-adjustable" exchange rate system, where the peso trades within a band and the central bank intervenes at the edges, is inherently unstable and contradicts Milei's free-market principles. This system creates perverse incentives, encourages speculation, and risks further reserve depletion. Bloomberg estimates that defending the peso until election day could cost up to $8 billion, a substantial sum for a country with critically low reserves. The U.S. Treasury's intervention may have bought time, but it has not altered the fundamental economic equation.
Defending an overvalued currency is not only economically unsound but also politically perilous. Floating the peso would restore monetary autonomy, discourage speculation, and signal confidence in Argentina's fiscal consolidation. It would also enhance the country's export capacity and its ability to earn foreign exchange for debt repayment. However, with elections imminent, the temptation to postpone necessary adjustments may prove irresistible. History suggests that the cost of such delays can be severe.
If Milei's efforts fail, the repercussions will extend beyond Argentina, representing a setback for market-oriented reformers across the region and serving as a cautionary tale for those who believe ideology alone can stabilize an economy. Argentina is once again testing the boundaries of economic orthodoxy, political resilience, and international patience, potentially adding another failed reform to its history.
AI summaries can miss context or contain errors. Check important details against the original video.