Key Concepts
- Vehicle Delivery Shortfall: Discrepancy between projected and actual vehicle deliveries.
- Consensus Estimates: Average predictions from financial analysts.
- Autonomy Prospects: Expectations surrounding Tesla’s self-driving capabilities and potential robo-taxi service.
- Growth Trajectory: The rate at which Tesla’s sales have historically increased, and the current slowdown.
- Robo-Taxi: Autonomous vehicles used for commercial ride-hailing services.
Disappointing Delivery Numbers & Revised Outlook
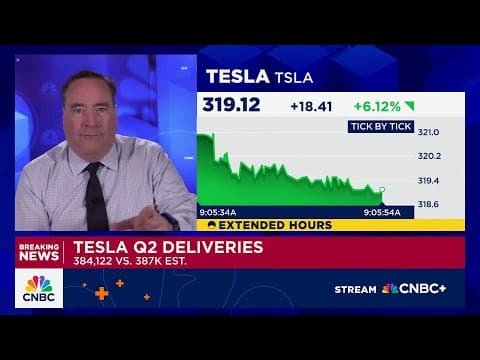
The discussion centers on recent disappointments in Tesla’s vehicle delivery projections. For the fourth quarter, the compiled consensus estimate was around 423,000 vehicles, representing a shortfall of approximately 22,000 vehicles compared to Bloomberg’s average estimate of 445,000. This indicates a significant miss in anticipated sales figures. Furthermore, the outlook for 2026 is also being revised downwards. Initial expectations projected sales of 3 to 3.5 million vehicles by this timeframe. Current consensus estimates, while higher than anticipated 2025 figures, are not substantially increased, signaling a deceleration in Tesla’s previously rapid growth. This represents a shift from the “gangbusters” year-over-year growth the company once experienced.
Shareholder Impact & Conflicting Narratives
The question is raised whether these delivery shortfalls and revised projections matter to Tesla shareholders. The response highlights a curious dynamic: despite these concerns, the stock price hasn’t significantly reacted negatively. This is attributed to a “coalescing consensus” around two seemingly contradictory ideas.
The first idea is a strong belief that Tesla is close to achieving full self-driving capability, potentially enabling a robo-taxi service. The second is a lack of corresponding optimism in the company’s overall sales outlook. The speaker points out the logical disconnect: “You would think that if there's so much optimism about this company's autonomy prospects, that you would see that sort of translate into, oh, my gosh, demand is going to shoot up and yet we're not seeing those, you know, move in unison with one another.” This suggests the market is compartmentalizing the potential of autonomous driving from current sales performance.
The Robo-Taxi Disconnect
A core argument presented is the lack of correlation between optimism regarding Tesla’s self-driving technology and projected vehicle sales. The expectation of a future robo-taxi fleet, which would theoretically drive significant demand, isn’t currently reflected in increased sales forecasts. This raises questions about the timeline and feasibility of achieving fully autonomous driving, and whether the market is accurately pricing in the potential impact of this technology. The speaker implies a skepticism that the anticipated benefits of self-driving will immediately translate into a surge in vehicle demand.
Data & Figures
- Q4 Vehicle Delivery Shortfall: 22,000 vehicles (423,000 consensus vs. 445,000 Bloomberg average).
- Initial 2026 Sales Expectations: 3 - 3.5 million vehicles.
- Current Trend: Downward revision of 2026 sales estimates.
Conclusion
The analysis reveals a growing disconnect between Tesla’s past growth trajectory, current delivery performance, and future projections. While optimism surrounding the development of self-driving technology persists, it hasn’t translated into increased sales expectations. This suggests the market is either skeptical about the near-term realization of full autonomy or is valuing the potential robo-taxi service separately from traditional vehicle sales. The continued lack of reaction from shareholders despite these concerns highlights a complex and potentially precarious situation for Tesla.
AI summaries can miss context or contain errors. Check important details against the original video.