Key Concepts
- Valuation Methods: Intrinsic Valuation, Pricing (Relative Valuation), Contingent Claims Valuation.
- Intrinsic Valuation Inputs: Cash flows from existing assets, value of growth, discount rate (cost of capital), terminal value.
- Growth Value Drivers: Revenue growth, profitability (margins), reinvestment (sales to capital ratio).
- Risk Inputs: Cost of capital (equity risk premium, default spread), failure risk.
- Value of Control: Expected value of control, hostile acquisitions, voting vs. non-voting shares, minority discounts in private companies.
- Pricing (Relative Valuation) Framework: Defining multiples, consistency test, uniform estimation, "play Moneyball" (data-driven analysis), embedded assumptions.
- Consulting Shortcuts: Economic Value Added (EVA), Cash Flow Return on Investment (CFROI), and other acronym-based metrics.
- Investment Philosophy: Intrinsic value vs. pricing, time horizon, storytelling vs. number crunching, importance of imagination and luck.
Valuation Methodologies and Applications
This session revisits the core concepts of valuation, integrating student project data to illustrate practical applications and challenges. The discussion centers on three primary valuation approaches: intrinsic valuation, pricing (relative valuation), and contingent claims valuation.
Intrinsic Valuation: The Core Equation
The foundation of intrinsic valuation is presented as a single, fundamental equation. The class has focused on refining the estimation of expected cash flows and adjusting the discount rate for risk.
-
Key Inputs:
- Cash Flows from Existing Assets: Derived from current financial statements.
- Value of Growth: This is a critical and challenging input. Growth creates value only if the company earns more than its cost of capital. Statistics indicate that approximately 70% of companies globally struggle to earn their cost of capital, making value-creating growth an exceptional achievement.
- Discount Rate: Risk is incorporated through the discount rate, typically via an equity risk premium for the cost of equity or a default spread for the cost of debt, leading to the cost of capital.
- Terminal Value: Used to provide closure in valuations for publicly traded companies that can theoretically exist in perpetuity. Common methods include the perpetual growth model or, for shorter-lived companies, a growing annuity or liquidation value.
-
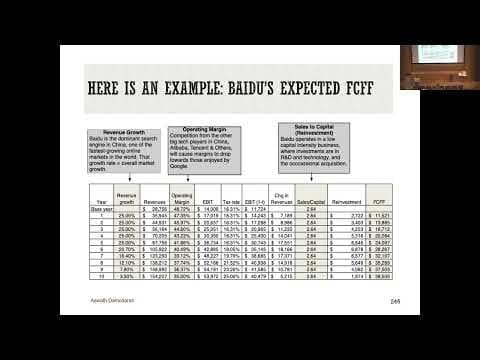
Drivers of Cash Flows (FCF Ginsu Model):
- Revenue Growth: Dependent on company size and market size. Large companies in mature markets (e.g., Costco, Walmart) have limited growth potential, while smaller companies in growing markets (e.g., Palantir) have higher potential.
- Profitability (Margins): Determined by unit economics. Companies with low variable costs per unit (e.g., software companies) can achieve higher margins than those with high variable costs (e.g., businesses where costs are 80% of revenue).
- Reinvestment (Sales to Capital Ratio): This lever connects growth and margins to cash flows.
-
Incorporating Risk:
- Cost of Capital: As mentioned above.
- Failure Risk: A discrete risk that is difficult to incorporate into the discount rate. This is assessed by considering the probability of a company not surviving, particularly relevant for small, money-losing, or distressed companies.
-
The Valuation Triangle: A framework for internal consistency in valuations, comprising:
- Growth: The potential for expansion.
- Reinvestment: Capital required to achieve growth.
- Risk: The uncertainty associated with the investment.
- Trade-offs: Higher growth often necessitates more reinvestment and potentially higher risk. Exceptionally successful companies (e.g., "Mag Seven") exhibit high growth, high margins, and low reinvestment.
Student Project Data and Analysis
The session analyzes data from student projects, where companies were valued using Discounted Cash Flow (DCF) models.
- Most Frequently Valued Companies: Boeing (8 students), Intel, DraftKings, Duolingo, Snowflake. These companies were often chosen due to their current "cusp" status, facing significant challenges or opportunities.
- Valuation Divergence: Even when valuing the same company, student valuations differed significantly due to choices made regarding growth, margins, and reinvestment assumptions.
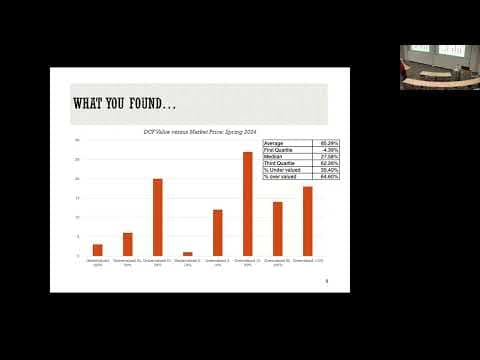
- DCF vs. Market Price:
- On average, student DCF valuations indicated that their median company was overvalued by approximately 28%.
- 65% of companies were found to be overvalued on a DCF basis, while 35% were undervalued. This is attributed to a strong market performance over the preceding years and pervasive negative news sentiment.
- Most Undervalued Companies: Azul, Publix, Joy, Target. The instructor noted a personal practice of investing in companies identified as undervalued by student recommendations.
- Most Overvalued Companies: Nissan was highlighted, with a potential currency mismatch or input error suggested as a cause for extreme overvaluation.
- Performance of Recommendations: Over five years, student buy recommendations, on average, outperformed the S&P 500, while sell recommendations underperformed. However, only about 60% of buy recommendations beat the market, and 45% of sell recommendations also beat the market, indicating significant noise and error. Buy recommendations on small and emerging market companies showed the most "heft."
Value of Control: Beyond Status Quo
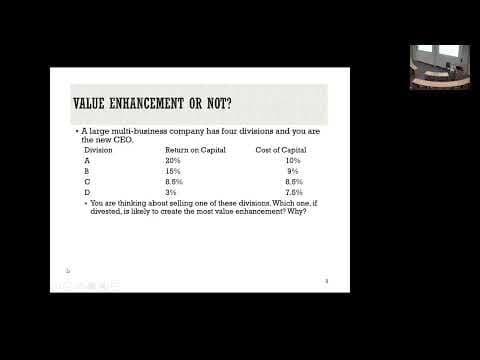
The discussion shifts to the "value of control," which considers how changing management or corporate structure can enhance a company's value.
-
Ways to Enhance Value:
- Increase Cash Flows from Existing Assets: Cost reduction, efficiency improvements, tax optimization.
- Increase Value from Growth: Growing more in good businesses, growing less in bad businesses.
- Reduce Cost of Capital:
- Optimizing the debt-to-equity mix.
- Eliminating mismatches between debt and assets (e.g., short-term debt for long-term assets).
- Reducing fixed costs.
- Making discretionary products less discretionary (lowering beta).
- Push out Stable Growth Period: Building competitive advantages.
-
Revaluing with Different Management: The core idea is to revalue a company assuming different management or strategic decisions. The difference between the status quo value and this "optimal" value represents the potential value of control.
- Factors Affecting Probability of Control Change:
- Corporate Governance Rules: Hostile acquisitions, voting rights structures.
- Access to Capital: Ability to fund activist campaigns.
- Company Size: Easier to change management in smaller companies.
- Family Control: Can significantly limit the possibility of management change.
- Factors Affecting Probability of Control Change:
-
Applications of Value of Control:
- Market Price of Publicly Traded Firms: The market price often reflects an expectation of potential control changes.
- Hostile Acquisitions: The acquirer can capture the value of control if they can implement changes more effectively than current management.
- Voting vs. Non-Voting Shares: Voting shares should trade at a premium due to the ability to influence management. The magnitude of this premium depends on the probability of successful change and the expected value of that change.
- Example (Embraer): A valuation showed a premium for voting shares due to the potential to change management, but the government's "golden share" limited this probability.
- Example (Facebook): The difference between super-voting and non-voting shares can reflect market sentiment on management's effectiveness.
- Private Company Valuation (Minority Discount): The inability to control a private company (owning less than 50%) leads to a discount on its value. The size of this discount depends on the quality of existing management and the potential for improvement.
Pricing (Relative Valuation): The Power of Comparables
Pricing involves valuing an asset based on what similar assets are trading for in the market.
- Four-Step Process for Deconstructing Multiples:
- Define the Multiple: Ensure clear agreement on what the multiple measures.
- Consistency Test: Numerator and denominator must align (e.g., equity value in numerator, equity earnings in denominator). Inconsistent multiples (e.g., Enterprise Value/Sales) can be misleading.
- Uniform Estimation: Apply the multiple consistently across all comparable companies.
- "Play Moneyball": Let the data guide what is high or low, rather than relying on rules of thumb.
- Embedded Assumptions: Multiples implicitly contain assumptions about cash flows, growth, and risk. These can be reverse-engineered by relating multiples to fundamental valuation models (e.g., Dividend Discount Model for equity multiples).
- Student Project Findings:
- EV/Sales was a common multiple, likely because it accommodates money-losing companies and avoids issues with negative earnings.
- A shift from equity multiples (like P/E) to enterprise value multiples (like EV/Sales) was observed.
- Pricing analysis indicated that the median company was underpriced, a stark contrast to the DCF findings of overvaluation. This highlights the difference between intrinsic and relative valuation.
- Palantir appeared on both the undervalued and overvalued lists, demonstrating the sensitivity of pricing to peer group selection.
- Option Pricing: Applicable to money-losing companies with significant debt, where the debt acts as a strike price for an option to liquidate. This can reveal additional value (optionality) not captured by traditional DCF.
Consulting Shortcuts and the Essence of Value
The session critiques consulting shortcuts that often use acronyms to simplify complex valuation, potentially obscuring fundamental drivers.
- Economic Value Added (EVA): Calculated as (Return on Invested Capital - Cost of Capital) * Invested Capital. While intended to measure value creation, EVA can be manipulated by management through accounting adjustments, leasing assets, or sacrificing long-term growth for short-term returns.
- Cash Flow Return on Investment (CFROI): A cash flow-based return on capital metric.
- Critique: These shortcuts can lead to perverse incentives if not grounded in the fundamental drivers of value: cash flows, growth, and risk. The instructor emphasizes that there are no new ways to estimate value; existing principles are often repackaged.
Synthesis and Conclusion
The session concludes by reinforcing key takeaways:
- Fundamentals Matter: Despite market sentiment, the underlying drivers of value (cash flows, growth, risk) remain paramount.
- Focus on the Big Picture: Avoid getting bogged down in minor details (e.g., precise cost of debt for companies with low debt ratios) when cost of equity is the dominant driver.
- Experience vs. Wisdom: Forty years of experience does not guarantee wisdom in investing; markets evolve, and past strategies may not apply.
- Imagination is Key: Creativity and the willingness to be wrong are the scarcest resources in investing and valuation.
- Valuation is a Tool, Not an End: Valuation is an estimate, not a definitive truth. It should not cause undue stress.
- Luck Plays a Role: While skill is essential, luck is an undeniable factor in investment success.
- Personalized Approach: Develop an investment philosophy that is uniquely yours, based on your understanding of market inefficiencies and your own strengths (storyteller or number cruncher).
- Bridging the Gap: Storytellers need to embrace numbers to discipline their narratives, while number crunchers need to develop the imagination to make bold, potentially contrarian, decisions.
- Index Funds as a Starting Point: For new investors, index funds can provide a stable base, allowing for gradual transition to individual stock picking as confidence and experience grow.
- Buy vs. Sell Recommendations: The historical data shows a tendency for more sell recommendations than buy recommendations, reflecting market sentiment and the difficulty of articulating a compelling "buy" story in uncertain times.
- Choosing the Right Valuation Method: The choice between intrinsic valuation and pricing depends on the asset type, marketability, and the investor's time horizon and job function.
- The Importance of Authenticity: Emulating investors like Warren Buffett means developing a clear, consistent, and authentic investment philosophy.
AI summaries can miss context or contain errors. Check important details against the original video.