Key Concepts
- Mortgage-Backed Securities (MBS): Bundles of mortgages sold as investments. Their yields influence mortgage rates.
- Treasury Yields: Yields on U.S. government debt, considered a benchmark for other bond yields.
- Spread (in finance): The difference between two bond yields (e.g., MBS yield vs. Treasury yield). A tight spread indicates limited room for MBS yields to fall further.
- Federal Reserve Mandate: Maintaining price stability (controlling inflation) and maximizing employment.
- Yield Curve Control: A monetary policy where a central bank targets specific yields on government bonds.
- Treasury Buybacks: The U.S. Treasury purchasing its own debt to reduce supply and potentially lower yields.
- Deficit Spending: When a government spends more money than it receives in revenue.
- Basis Points: A unit of measurement equal to 0.01% (e.g., 100 basis points = 1%).
The Administration's Efforts to Lower Interest Rates & Impact on Midterms
The primary focus of the current administration is to improve consumer sentiment, particularly regarding affordability, leading up to the midterm elections. A key component of this is lowering mortgage rates, as housing affordability is a significant driver of overall sentiment. Household sentiment is currently weak, making this a priority.
The $200 Billion MBS Purchase Program
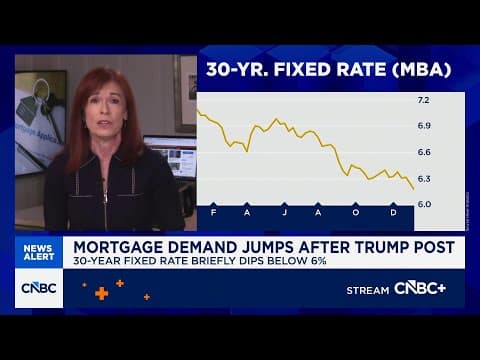
The administration announced a $200 billion program for Fannie and Freddie to purchase mortgage-backed securities (MBS). The rationale is that increased demand for MBS will raise their prices and, consequently, lower their yields, translating to lower mortgage rates for consumers. However, the effectiveness of this program is limited by the historically tight spread between MBS yields and Treasury yields.
The Tight Spread Between MBS and Treasury Yields – A Major Obstacle
Currently, the spread between MBS yields and Treasury yields is exceptionally narrow. This means there is limited room for MBS yields to fall further without going below Treasury yields, which are considered a lower-risk benchmark. Therefore, simply increasing demand for MBS won’t significantly lower mortgage rates unless Treasury yields are also reduced. The 10-year Treasury yield was recently at just under 4.2%.
Federal Reserve’s Role & Limitations
While the Federal Reserve has been cutting interest rates, its direct influence is primarily on short-term rates. The transmission of these cuts to longer-term Treasury yields (like the 10-year) has been incomplete. Since the beginning of last year, one-month yields have fallen by 7/10 of a percentage point, while 10-year yields have only decreased by 4/10 of a percentage point. Mortgage rates are more closely tied to longer-term Treasury yields.
Factors Preventing Lower Long-Term Treasury Yields
Two primary factors are hindering the decline of longer-term Treasury yields:
- Humongous Federal Deficit: The U.S. federal deficit has reached record levels, exceeding even the peak during the 2009 financial crisis. This raises concerns about future inflation and the government’s ability to service its debt, pushing investors to demand higher yields.
- Criminal Subpoena to Jerome Powell: A criminal subpoena issued to Federal Reserve Chairman Jerome Powell regarding renovations at Fed office buildings, while potentially politically motivated (described by the Wall Street Journal as “lawfare for dummies monetary edition”), introduces uncertainty and could unsettle markets.
The Risk of Politicizing the Federal Reserve
The administration’s pressure on the Federal Reserve to lower interest rates raises concerns about the independence of the central bank. Maintaining an independent Fed is crucial to prevent chronically low interest rates that could lead to runaway inflation. The White House attempting to influence monetary policy could spook the bond market, leading investors to sell bonds and drive yields up, the opposite of the desired effect. The market has largely shrugged off the subpoena to Powell so far, suggesting continued faith in the Fed’s commitment to its mandate.
Potential Strategies to Lower Treasury Yields
John Hill of Barclays outlined three potential strategies the Treasury could employ to lower Treasury yields:
- Regulatory Adjustments: Tweaking capital rules to make Treasuries more attractive to investors. However, these adjustments take time and are already largely priced into the market.
- Treasury Buybacks: The Treasury purchasing its own debt to reduce supply and increase prices.
- Supply Adjustments: Reducing the issuance of long-term Treasury bonds. This is potentially the most impactful but is constrained by the need to fund the large federal deficit.
Market Response & Future Outlook
Despite the administration’s efforts and the political pressure on the Fed, the bond market has not panicked. This suggests investors still believe the Fed is prioritizing its mandate over political considerations. However, the situation remains fluid, and the administration is likely to continue exploring options to lower mortgage rates before the midterm elections. Predicting the future path of mortgage rates is difficult, but the administration’s actions and the broader macroeconomic environment will be key factors. The administration is expected to continue pursuing creative solutions to improve affordability and consumer sentiment.
Notable Quotes
- “Treasuries are considered a super low-risk investment. So, their yields are often a starting point for other yields on other investments.” – Jack How, explaining the benchmark role of Treasury yields.
- “If you make investors think that there's going to be some White House takeover or strongarmming of Fed policy that we're going to set interest rates unduly low, the bond market isn't going to like it.” – Jack How, highlighting the potential negative consequences of politicizing the Fed.
- “The market is basically not priced for policy rates to dip below 3%.” – John Hill, Barclays, indicating the market’s current expectations for future interest rate cuts.
Technical Terms Explained
- Yield Curve: A graph showing the yields of bonds with different maturities.
- Basis Points: A unit of measurement equal to 0.01% (e.g., 100 basis points = 1%).
- Auction Sizes: The amount of debt the Treasury offers for sale at regular auctions.
- Neutral Stance (of monetary policy): A policy setting where interest rates are neither stimulating nor restricting economic growth.
Logical Connections
The discussion progresses logically from identifying the administration’s goal (improving sentiment before midterms) to analyzing the obstacles to achieving that goal (tight MBS/Treasury spread, federal deficit, political pressure on the Fed). It then explores potential solutions and assesses their feasibility, culminating in an outlook for mortgage rates. The conversation consistently links macroeconomic factors to the political context and market implications.
AI summaries can miss context or contain errors. Check important details against the original video.