Key Concepts:
- Palantir's growth in the US commercial segment
- EIB (Exact Inference Based) contribution to Palantir's revenue
- Comparison with Microsoft Azure's AI contribution to growth
- Data warehousing market and competitors (Teradata, Oracle, Snowflake, Databricks)
- Hyperscalers (Microsoft) and their competitive positioning with Copilot
- Valuation multiple and sustainability of growth
- Net new ARR (Annual Recurring Revenue) of hyperscalers vs. Palantir
Palantir's Growth in the US Commercial Segment
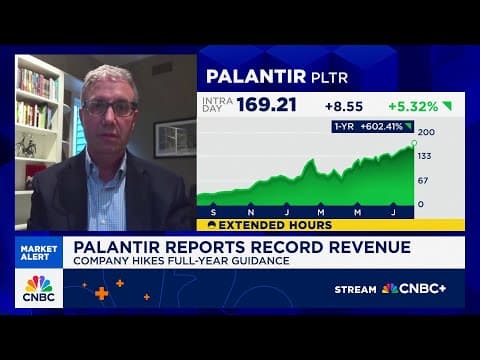
The US commercial segment is a key area of excitement for Palantir. The company experienced a growth rate of 93% for the full year, and their guidance projects 85% growth. This segment has a run rate exceeding $1.2 billion, indicating substantial scale.
Uncertainty Regarding EIB Contribution
A key question remains about the contribution of EIB (Exact Inference Based) to Palantir's top-line growth. While Palantir's overall growth is impressive, the specific impact of EIB is not clearly quantified.
Comparison with Microsoft Azure's AI Growth
Microsoft Azure's AI contribution to growth is 17%, with an overall growth rate of 39%. Palantir grew 48%, but the portion attributable to AI is unknown. Palantir's business model relies on contract wins, and while backlog growth and remaining deal value on the commercial side are reported, the lack of specific AI contribution data makes it difficult to assess the true drivers of growth.
Valuation and Transparency
Given Palantir's high valuation multiple, investors seek greater transparency regarding the revenue flow-through from specific technologies like EIB. A more detailed breakdown of numbers is needed to justify the valuation.
Market Share and Competition
Palantir's core business is data warehousing. Competitors include legacy vendors like Teradata and Oracle, as well as cloud-based companies such as Snowflake and Databricks. Databricks is also experiencing strong growth. As Palantir expands in the commercial sector, its growth will likely come at the expense of these competitors.
Hyperscalers and Competitive Positioning
Hyperscalers, particularly Microsoft, are also vying for a share of the market. Microsoft's Copilot is positioned to address some of the same use cases that Palantir targets.
Sustainability of Growth and Valuation
The sustainability of Palantir's commercial-side growth is crucial for maintaining its valuation. The net new ARR (Annual Recurring Revenue) of hyperscalers significantly exceeds that of Palantir, given Palantir's smaller size.
Conclusion
Palantir's impressive growth in the US commercial segment is driving excitement, but questions remain about the specific contribution of technologies like EIB and the long-term sustainability of this growth in the face of competition from established players and hyperscalers. Greater transparency and a more detailed breakdown of revenue drivers are needed to justify Palantir's high valuation.
AI summaries can miss context or contain errors. Check important details against the original video.