Key Concepts
- Monetary policy settings unchanged (wait-and-see approach)
- Trade uncertainty and US tariffs
- Singapore dollar (SGD) appreciation
- Economic growth slowdown in H2
- Inflationary expectations contained
- Front-loading activities and inventory stocking
- Federal Reserve (Fed) policy decision
Singapore's Monetary Policy Amid Global Trade Uncertainties
MAS Decision and Rationale
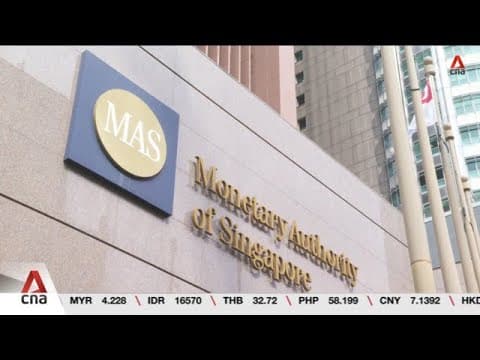
The Monetary Authority of Singapore (MAS) has kept its monetary policy settings unchanged for the first time this year, adopting a "wait and see" approach. This decision comes after two consecutive easings in the first half of the year aimed at slowing the rate of appreciation of the Singapore dollar. The MAS is pausing to assess the risks to economic growth stemming from US tariffs and broader trade uncertainties.
- Key Point: MAS believes current monetary policy settings are consistent with medium-term price stability.
- Context: This decision aligns with other global central banks also holding steady amid trade uncertainties.
Impact of Trade Uncertainties and Policy Response
The fallout from global trade uncertainties will take time to fully materialize in the economy, and policy responses will also have a lagged effect.
- Q3 Outlook: Oxford Economics estimates that Q3 represents a trough in terms of investment pullback and payback effects from strong exports in H1.
- Potential for Further Easing: Policy makers might respond more proactively in the second half of the year, potentially in October, with further easing measures.
- Inflation: Singapore's output gap is likely to be broadly neutral this year, containing inflationary expectations.
- Resilient Sectors: Certain sectors like services and construction are expected to show some resilience to tariffs, providing tailwinds to the economy.
Future Policy Easing and Global Economic Slowdown
The speaker anticipates further policy easing in the next MAS policy review due to significant uncertainty and downside risks to the global economy in the second half of 2025.
- Working Assumption: A "wait and see" approach in the July meeting, followed by a more decisive easing stance in the October review.
- Trigger: This easing would coincide with more obvious signs of economic weakness in Singapore and a significant deceleration in key partner economies like China and the US.
- Reactive Approach: Policy makers are expected to be more reactive to data weakness rather than preemptive.
Singapore Dollar Strength and Export Competitiveness
The impact of currency strength on exports is expected to be marginal.
- US Dollar Stability: The US dollar is expected to remain broadly stable at current levels.
- Regional Currency Trends: The Singapore dollar is expected to remain somewhat strong, but regional currencies are generally expected to benefit from a weaker US dollar.
Front-Loading Activities and Inventory Stocking
The resilience of Singapore's GDP and exports may be partly due to front-loading activities, which poses a downside risk.
- Front-Loading: Companies are front-loading activities to avoid higher tariffs and anticipate a slowdown in subsequent quarters.
- Unwinding: This front-loading is expected to unwind over at least two quarters, leading to relative export weakness.
- Inventory Stocking: There are concerns about inventory building, where companies are filling shelves with unsold goods. If this inventory unwinds, it could further drag down growth.
Federal Reserve Policy Decision
The Federal Reserve's policy decision is expected to primarily affect currencies.
- Expectation: The Fed is expected to stay on hold.
- Impact: Rate differentials with Asia, including Singapore, are expected to remain fairly stable, leading to a manageable fallout.
Conclusion
The MAS's decision to hold monetary policy steady reflects a cautious approach amid global trade uncertainties. While some sectors show resilience and inflation remains contained, downside risks persist, particularly from the potential unwinding of front-loading activities and inventory stocking. Further policy easing is anticipated in the coming months, contingent on economic data and the actions of other central banks, particularly the Federal Reserve.
AI summaries can miss context or contain errors. Check important details against the original video.