Key Concepts
- AI Infrastructure Capex: Capital expenditure by major tech firms specifically allocated to Artificial Intelligence hardware and software.
- Supply Shock: A sudden disruption in the supply chain—specifically energy transportation—that causes price volatility.
- Binding Constraints: Economic limits reached when essential resources (like energy) become scarce, hindering production and logistics.
- Cyclical Companies: Businesses whose performance is highly sensitive to the broader economic cycle (e.g., industrial, travel, and consumer spending sectors).
- Mag-7 (Magnificent Seven): A group of high-performing, large-cap US technology stocks that are primary drivers of current market sentiment.
- Straits of Hormuz: A critical maritime chokepoint for global oil transit, the closure of which is cited as a major risk factor for global energy prices.
1. The AI Trade as an Economic "Escape Hatch"
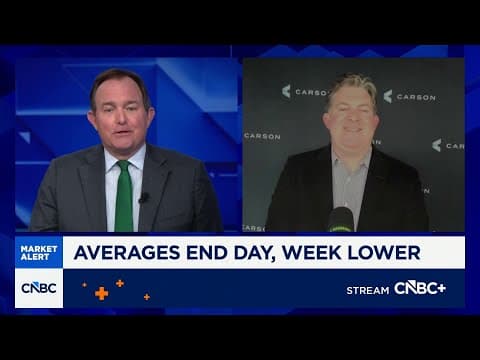
Steven Whiting, Chief Investment Strategist at CIO Group, argues that the current market performance is bifurcated. While the broader economy faces headwinds, the AI sector acts as an "escape hatch" for investors.
- Independence from Cyclicals: AI-related software and hardware investments are largely decoupled from the cyclical performance of the global economy.
- Funded Commitments: Because these Capex (Capital Expenditure) plans are already funded and "bets are on the table," they are expected to proceed regardless of fluctuations in consumer spending, travel, or industrial activity.
- Earnings Drivers: The market is currently pricing in an 88% gain in semiconductor EPS (Earnings Per Share) for the year, making the upcoming earnings reports from the four largest AI infrastructure spenders critical for market direction.
2. Energy Supply Shocks and Global Economic Impact
Whiting highlights the "Straits of Hormuz" situation as a significant risk factor that is beginning to move from a localized issue to a global economic constraint.
- Binding Constraints: The longer the straits remain closed, the more the global economy will hit "binding constraints." Logistics require energy; therefore, energy shortages will eventually impact the ability to move goods globally.
- Market Reaction: The energy futures curve has already shifted, with oil prices for year-end delivery rising by $15. Whiting warns that this indicates a growing problem for cyclical companies, particularly those in Europe and Asia that are more directly exposed to these supply chain disruptions.
- Binary Recovery: Whiting characterizes the recovery of these cyclical sectors as "binary." Once the supply shock—defined by transportation and storage issues—is resolved, energy prices should normalize, allowing these sectors to recover.
3. Monetary Policy and the Federal Reserve
The discussion touches on the limitations of the Federal Reserve in the current environment.
- Policy Efficacy: Whiting questions the ability of monetary policy to "change the needle" when the economy is facing a supply-side shock rather than a demand-side issue.
- Inflation vs. Growth: There is skepticism regarding the Fed’s ability to guarantee 2% inflation while simultaneously managing an economy under the pressure of supply constraints.
- Labor Market Sentiment: Despite fluctuating monthly data, consumer sentiment remains negative regarding the path of employment and prices, suggesting a disconnect between official statistics and the lived experience of the consumer.
4. Investment Outlook and Risks
Whiting expresses a shift toward a more cautious stance, balancing the "boom" of AI investment against the "shock" of energy volatility.
- Capex Intensity: The four largest tech companies increased their full-year Capex by $94 billion in their previous reports. Investors are now looking to see if this spending trajectory continues into 2028 and 2029.
- Nominal Growth vs. Inflation: A significant concern raised is that the combination of heavy AI-related Capex and energy supply shocks may lead to higher nominal growth, but with a larger portion of that growth being driven by inflation rather than real productivity gains.
Synthesis and Conclusion
The market is currently defined by a tension between the massive, independent growth of AI infrastructure and the systemic risks posed by energy supply shocks. While the S&P 500 has shown resilience due to its heavy weighting in tech, the underlying global economy is increasingly vulnerable to energy-related constraints. The primary takeaway is that while AI spending provides a buffer, the long-term economic outlook remains precarious, with the risk that current growth trends may be increasingly inflationary rather than sustainable.
AI summaries can miss context or contain errors. Check important details against the original video.