Don’t Skip This “Free Money” Step
By The Money Guy Show
Key Concepts
- Financial Order of Operations: A prioritized sequence for managing finances.
- Employer Match: Funds contributed by an employer to an employee’s retirement account, typically based on employee contributions.
- Tax-Deferred Growth: Investment gains are not taxed until withdrawal.
- Tax-Free Withdrawals: Withdrawals from certain accounts (Roth IRA, Roth 401k, HSA) are not subject to taxation under specific conditions.
- Roth IRA: A retirement savings account where contributions are made with after-tax dollars, but qualified withdrawals are tax-free.
- Roth 401(k): A retirement savings plan offered through employers, similar to a Roth IRA in its tax treatment.
- Health Savings Account (HSA): A tax-advantaged savings account used to pay for qualified healthcare expenses.
Prioritizing Employer Match & Tax-Free Accounts
The discussion centers on the second step in a recommended “financial order of operations,” focusing on maximizing benefits from employer-sponsored retirement plans and prioritizing tax-advantaged accounts. The core argument is that securing an employer match is crucial due to the “free money” it represents, coupled with inherent tax advantages.
Specifically, the speaker highlights the benefit of an employer match – funds contributed by the employer to an employee’s retirement account, often proportional to the employee’s own contributions. This is described as a “twofur” (likely a colloquialism for a significant benefit) because it’s essentially free money. Beyond the direct contribution, the speaker notes that contributions to these plans also offer certain tax benefits.
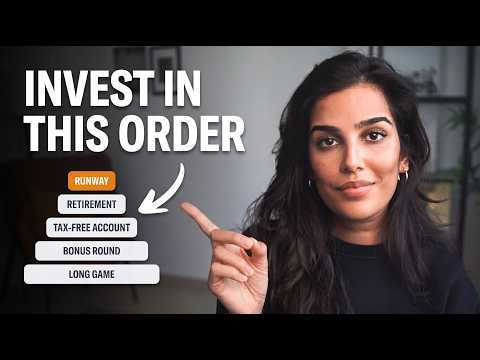
Following the maximization of the employer match, the next priority is to contribute to tax-free accounts. These include Roth IRAs, Roth 401(k)s, and Health Savings Accounts (HSAs). The key characteristic of these accounts is that while contributions are generally not tax-deductible in the present (with the exception of potential deductions related to HSAs), the funds within these accounts experience tax-deferred growth. This means investment gains are not taxed until withdrawal. Crucially, qualified withdrawals from these accounts are entirely tax-free.
The speaker emphasizes that this tax-free withdrawal feature is a significant advantage, allowing individuals to accumulate wealth without future tax liabilities, provided withdrawals meet the qualification criteria. No specific figures or contribution limits were mentioned, but the focus was on the principle of prioritizing these accounts after securing the employer match.
The logical connection between these two steps is clear: first, capitalize on guaranteed returns (employer match), then focus on maximizing long-term, tax-advantaged growth.
Synthesis
The primary takeaway is the importance of a strategic approach to financial planning, beginning with securing employer matching contributions and then prioritizing tax-free investment vehicles like Roth IRAs, Roth 401(k)s, and HSAs. This approach aims to maximize returns and minimize future tax burdens, ultimately leading to more efficient wealth accumulation.
Chat with this Video
AI-PoweredLoad the transcript when you're ready to chat so the initial page stays lighter.
Related Videos

Financial Advisors React to Wild Money Advice ft. @ErinTalksMoney
The Money Guy Show

Can You Retire on $1.5 Million?
The Compound

Is the Great Reset Happening? Mark Moss Explains What's Changing - Robert Kiyosaki
The Rich Dad Channel

WTF Just Happened To Your Retirement Accounts?!
Graham Stephan

How To Win Financially Based On Your Income ($50K, $100K, $150K, $300K)
The Money Guy Show

The Stark Reality of What a $1.5M Retirement Looks Like in 2026
The Money Guy Show
The Smartest Order to Invest Your Money (Step-by-Step)
Nischa