Key Concepts
- Domino's Pizza Group (UK & Ireland)
- Domino's Pizza (NASDAQ)
- Domino's (Australia/Asia/Europe)
- Compounder Stock
- Margin of Safety
- Price-to-Earnings (P/E) Ratio
- Dividend Yield
- Free Cash Flow (FCF)
- Earnings Per Share (EPS)
- Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA)
- Market Share
- Asset-Light Model
- Acquisition Strategy
- Debt-to-Income Ratio
- Return on Capital
- Risk-Reward Assessment
- Inflation
- Economic Downturn
Domino's Pizza Group (UK & Ireland)
Financial Performance and Current Situation
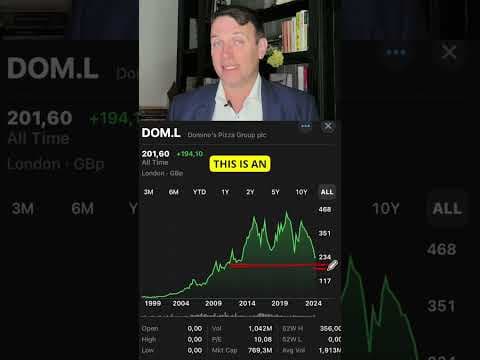
Domino's Pizza Group (UK & Ireland) is described as a "compounder" stock that is currently experiencing a temporary downturn. While sales are flat, free cash flows are slightly down, and EBITDA and EPS have also decreased, the company remains profitable. The decline is attributed to a general market slowdown in the UK and the impact of inflation on consumers globally. Margins and EPS have seen a reduction, with EPS down 29%, but the underlying profitability and cash flow generation remain strong.
Dividends and Buybacks
The company has a strong history of returning capital to shareholders, having distributed over £500 million in dividends and buybacks. This figure is significant when compared to the current market capitalization of £775 million, suggesting that if this level of capital return is sustained over the next five years, it could represent 70% of the market cap, potentially leading to good investor returns.
Growth Strategy and Market Position
Domino's Pizza Group is actively seeking opportunities for a second brand through acquisitions, operating under strict financial and strategic guidelines. Despite the market slowdown, the company is increasing its market share, indicating that the challenges are market-driven rather than company-specific. This suggests a stable business model that is resilient to economic headwinds. The outlook is projected to be flat, with potential for improvement if successful acquisitions can be scaled effectively, similar to their existing asset-light platform.
Financial Deep Dive
The company has approximately £600 million in debt, which is considered substantial relative to its market cap. However, ongoing share buybacks are reducing equity. The business operates on an asset-light model, generating strong cash flows. Long-term trends show growth, despite past "hiccups." Free cash flow yield is around 10-11%, with low capital expenditures, indicating a good return on capital, a metric favored by investors like Warren Buffett.
Risk and Reward Assessment
The current valuation, with a P/E ratio around 10 and a 10% free cash flow yield, presents an interesting proposition. The primary uncertainty lies in the success of their acquisition strategy for future growth. The company previously attempted to acquire WinkTop but was outbid by private equity. The potential for future acquisitions, possibly financed with additional debt, carries both upside (transformative growth) and downside (failed integration, similar to "Jack in the Box" scenarios). The UK market is expected to remain stable, and even if growth falters, a 5% dividend yield offers a baseline return. The possibility of repackaging and selling the business to private equity is also mentioned as a potential exit strategy.
Domino's Pizza (NASDAQ)
Financials and Valuation
In contrast to the UK entity, Domino's Pizza on NASDAQ has a P/E ratio of 25 and a dividend yield of 1.64%. The company is still growing, with a business split between the US and international markets. Revenues and profits are growing accordingly. Long-term debt is being used for share buybacks, leading to negative equity. The stock is considered fairly valued in the current market but expensive from a value investor's perspective.
Domino's (Australia/Asia/Europe)
Financial Performance and Challenges
This entity, described as an "intricate mess" and "ugly," has a net profit of A$160 million against an Australian dollar market cap, implying a P/E ratio of 10 or 15. However, the company is facing significant challenges with no growth. The business model, successful in the UK and US, is struggling in other regions, with specific mention of a "debacle" in Italy and closures in Japan. Global EBITDA is down, and scaling globally is proving difficult. Restructuring and organizational changes are ongoing, with a note that these often become recurring.
Balance Sheet and Risk Profile
The balance sheet shows significant risk, with non-current borrowings and other liabilities indicating debt that is eight times net income. This is considered a "very very risky" situation. However, the potential upside is substantial if the company can recover and achieve its past valuations of 5x or 10x its current state. This is categorized as a "risky bet."
Comparative Analysis and Conclusion
The video compares three "Domino's" entities, placing them on a risk-reward quadrant. Domino's Pizza Group (UK & Ireland) is positioned around a 10% return with moderate risk, potentially slightly higher due to UK economic factors. Domino's (Australia/Asia/Europe) is considered a riskier bet with potential for higher returns if it can turn around its performance. Domino's Pizza (NASDAQ) is seen as fairly valued to expensive, with good growth but a higher P/E.
The speaker emphasizes that investors don't need to buy all these stocks but should identify one or two good opportunities over time. The analysis will continue with updates on earnings and acquisitions. The speaker suggests that Domino's Pizza Group (UK & Ireland) might be a suitable candidate for a diversified portfolio, potentially to be considered at the end of the month.
Synthesis/Conclusion
The YouTube video provides a detailed comparative analysis of three different "Domino's" pizza companies: Domino's Pizza Group (UK & Ireland), Domino's Pizza (NASDAQ), and Domino's (Australia/Asia/Europe). The UK entity is presented as a potentially undervalued compounder facing a temporary market downturn, offering a strong free cash flow yield and a significant dividend, with future growth contingent on successful acquisitions. The NASDAQ-listed company is deemed fairly valued to expensive with solid growth prospects. The Australian/Asia/Europe entity is highlighted as a high-risk, high-reward situation with significant debt and operational challenges but the potential for substantial recovery. The overarching takeaway is to carefully assess the risk-reward profile of each entity, with the UK company appearing to be the most compelling for a starting position in a diversified portfolio, pending further developments in its acquisition strategy.
AI summaries can miss context or contain errors. Check important details against the original video.