Key Concepts
- Covered Calls: A strategy where an investor owns an underlying asset (like stocks) and sells call options on that asset.
- Distribution Yield: The cash payments distributed by a fund to its investors, often derived from option premiums in covered call strategies.
- Total Return: The actual profit or loss on an investment, including income (distributions) and capital appreciation.
- Expected Return: The anticipated profit or loss from an investment over a period, considering probabilities and potential outcomes.
- Strike Price: The predetermined price at which the option holder can buy the underlying asset.
- Option Premium: The price paid by the buyer of an option to the seller for the right to buy or sell an asset at a specific price.
- Delta: A measure of an option's sensitivity to changes in the price of the underlying asset.
- Equity Risk Premium: The excess return that investing in the stock market provides over a risk-free rate.
- Mean Reversion: The tendency of stock prices to revert to their historical average over time.
- Volatility Risk Premium: The difference between the implied volatility of an option and its realized volatility, which can be earned by option sellers.
- Management Expense Ratio (MER): The annual fee charged by a fund to cover its operating expenses.
- Trading Expense Ratio (TER): The annual cost of trading within a fund, expressed as a percentage of assets.
The Devil's Bargain: Why Covered Calls Are Not Passive Income
This video argues that the perceived "passive income" generated by covered call strategies is a misleading and potentially detrimental financial strategy, particularly for long-term investors. Ben Felix, Chief Investment Officer at PWL Capital, explains that while covered calls generate income through option premiums, this income comes at the cost of reduced expected total returns and increased risk.
1. The Misconception of Income vs. Returns
A core argument is that distribution yields from covered call funds are often presented as income or expected returns, which is financially inaccurate.
- Distribution Yield vs. Total Return: Distribution yields represent cash payouts, often from option premiums, but they do not reflect the overall performance of the investment. Total return, which includes both distributions and capital appreciation, is the true measure of investment success.
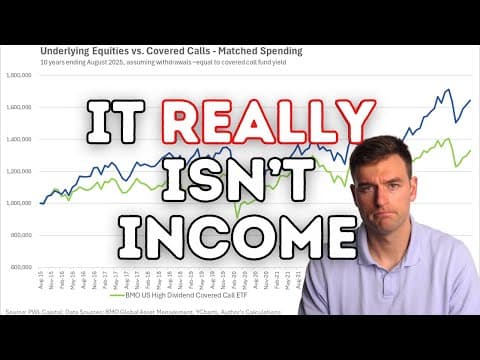
- Inverse Relationship: Covered call strategies exhibit an inverse relationship between distribution yields and expected total returns. Higher distribution yields mechanically lead to lower expected total returns.
- Marketing Tactics: Fund managers leverage high distribution yields to attract investors, often misrepresenting them as sustainable income or expected returns. This is described as "indifference for the truth" rather than an outright lie.
2. Mechanics of Covered Calls and Reduced Expected Returns
The video delves into the technical aspects of how selling call options impacts investment performance.
- Selling a Call Option: This involves selling the right to buy an underlying stock at a specific strike price in exchange for a premium.
- Liability Creation: Selling a call option creates a liability for the fund. If the stock price rises above the strike price, the fund must sell the stock at a price below its market value, capping upside potential.
- Reduced Exposure to Underlying Equity: Selling a call option reduces the investor's exposure to the underlying stock, measured by "delta." A higher delta in a short call option means lower exposure to the underlying asset.
- Asymmetric Risk Profile: Covered calls result in an asymmetric risk profile: investors retain most of the downside risk while their upside potential is capped at the strike price. This means investors participate in market downturns but miss out on significant recoveries.
- Elimination of Mean Reversion: For long-term investors, stocks historically exhibit mean-reverting behavior (performing better after poor performance). Covered calls eliminate this beneficial characteristic by capping upside, hindering recovery from downturns.
3. The Volatility Risk Premium: A Fading Hope
While the volatility risk premium (VRP) is sometimes cited as a potential benefit for option sellers, the video argues it's insufficient to offset the downsides of covered calls.
- VRP Explained: Equity options are often priced with implied volatility higher than realized volatility, creating an opportunity for option sellers to earn a premium for taking on the risk of extreme events.
- Insufficient Offset: Since approximately 2011, the VRP has not been large enough to compensate for the reduction in equity exposure caused by selling options, leading to poor performance in back-tested and live covered call strategies.
- Crowded Trade Effect: The proliferation of retail funds chasing covered call strategies may have diminished the VRP.
4. Real-World Performance: Live Fund Analysis
The video presents data from actual covered call ETFs to demonstrate the theoretical arguments.
- Beimo Covered Call Utilities ETF:
- Launched: October 20, 2011.
- Current Distribution Yield: 7.37% (vs. 3.43% for underlying equity ETF).
- Performance: Trailed the underlying by an annualized 2.6% since inception. Underperformed in over 70% of 3-year rolling periods and nearly 85% of 4-year rolling periods.
- Beimo Covered Call Canadian Banks ETF:
- Launched: January 28, 2011.
- Current Distribution Yield: 6.13% (vs. 3.61% for underlying equity ETF).
- Performance: Underperformed by an annualized 2.71% since inception. Outperformed in less than 1% of rolling 3-year periods.
- Global X S&P TSX 60 Covered Call ETF:
- Launched: March 16, 2011.
- Current Distribution Yield: 7.67%.
- Performance: Trailed the iShares S&P TSX 60 ETF by 3.65% since inception. Trailed in 92% of 3-year rolling periods.
- Hamilton ETF's Yield Maximizer ETF Series:
- Targets yields well over 10%.
- US Equity Yield Maximizer ETF targets 12% distribution yield.
- Performance: Underperformed an S&P 500 ETF by an annualized 4.48% over its short history.
- JPMorgan Equity Premium Income ETF (JAPI):
- Gained popularity for outperforming the S&P 500 in 2022.
- Performance: Underperformed an S&P 500 ETF by 5.92% since inception (May 2020). The underlying portfolio is actively managed, making a direct comparison difficult.
- Single Stock Covered Call ETFs (e.g., TSLY on Tesla):
- Exhibit astronomical distribution yields (e.g., TSLY at 48.59%).
- Performance: TSLY has underperformed Tesla by over 20% annualized since inception (November 2022). This highlights the inverse relationship between high derivative income yields and low expected returns.
5. Higher Yields Exacerbate Downsides
The pursuit of higher distribution yields through strategies like selling at-the-money options (lower strike prices) amplifies the negative aspects of covered calls.
- Lower Strike Prices: Lead to higher distribution yields, but also higher short delta (less exposure to the underlying) and a tighter cap on upside performance.
- Targeting High Yields: Products targeting yields over 10% often show significant underperformance compared to their underlying benchmarks.
6. Fees and Transaction Costs
Covered call funds typically incur higher fees than funds holding their underlying equities.
- Average MER: 0.63% for covered call funds vs. 0.25% for underlying equity funds.
- Average TER: 0.16% for covered call funds vs. 0% for underlying equity funds.
- Cost Premium: Investors pay a significant premium for the downsides of covered calls.
7. Conclusion: A Detrimental Strategy for Long-Term Investors
Ben Felix concludes that covered calls are not suitable for long-term investors seeking to fund their retirement or inflation-adjusted spending.
- Limited Upside, Uncapped Downside: The strategy limits potential gains while leaving investors exposed to the full downside of the underlying asset, only slightly mitigated by the option premium.
- Capital Depletion Risk: High distribution yields, when spent, can lead to rapid depletion of capital, especially when combined with lower expected returns and uncapped downside.
- Psychological Trap: The allure of high distribution yields can be a psychological trap, leading investors to make poor decisions, such as borrowing money to invest in these funds.
- "Indifference to the Truth": Marketing covered call yields as sustainable income or expected returns is described as "indifference to the truth," especially when contrasted with the safety of treasury bills.
- No Unique Offering: Covered calls do not offer anything unique compared to holding cash, except with limited upside and uncapped downside. They are more likely to harm than improve expected investor outcomes.
- Compounding Detriment: The negative effects of covered calls compound over time, creating a widening performance gap between these strategies and their underlying equities.
The video emphasizes that while some sophisticated investors might use covered calls to access the volatility risk premium, this is an esoteric strategy not relevant to the typical household investor. The marketing of these products based on yield, which is inversely related to expected returns, is fundamentally flawed.
AI summaries can miss context or contain errors. Check important details against the original video.