Key Concepts
- GDP (Gross Domestic Product): A measure of the total value of goods and services produced within a country's borders.
- Tariffs: Taxes imposed on imported or exported goods.
- Monetary Policy: Actions undertaken by a central bank to manipulate the money supply and credit conditions to stimulate or restrain economic activity.
- Inflation: A general increase in prices and fall in the purchasing value of money.
- Structural Adjustment: Economic policies aimed at correcting imbalances in an economy, often in response to external shocks like trade changes.
- Flash Estimate: A preliminary estimate of economic data released before the full, detailed report is available.
- Subsectors: Specific segments within a broader industry (e.g., wood manufacturing within manufacturing).
Economic Overview: Canadian GDP in October & November
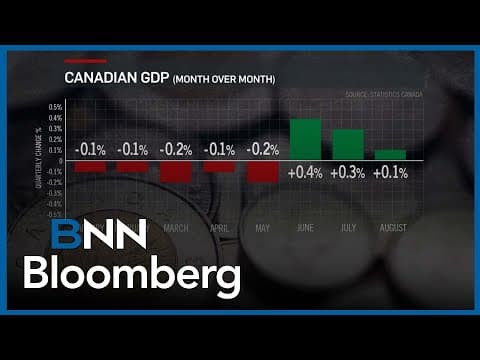
The Canadian GDP experienced a decline of 0.3% in October, effectively negating the 0.2% gain observed in September. Despite this setback, economist LJ Valencia of Desjardins suggests Canada has likely avoided a recession, though headwinds remain for the Canadian economy. The discussion centers on analyzing the factors contributing to this fluctuation and the potential implications for monetary policy.
Manufacturing Sector Analysis
September’s manufacturing strength was largely driven by machinery manufacturing, but this contribution diminished significantly in October. A key factor identified in the October decline was a decrease in wood manufacturing, directly attributed to newly implemented tariffs on wood products. Specifically, tariffs on cabinetry and furniture were cited as a defining factor impacting this subsector. While other potential influences exist, such as the postal worker strike affecting transportation and warehousing, and the Alberta teacher strike impacting public sector services, the tariff impact on wood manufacturing is clearly identified.
Trade & Retail Performance
Retail trade experienced its second consecutive month of decline in October, and wholesale trade fell for the second time in three months. While tariffs could be a contributing factor to the retail decline, Valencia cautions against drawing definitive conclusions from a single data point, emphasizing the need for further data to confirm a trend. The overall assessment points to weakness across multiple subsectors, as evidenced by the monthly GDP data.
Construction Sector Decline
The construction sector saw an unusual decline for the first time in six months. Valencia reiterates the caution regarding single data points, noting that factors like housing starts and overall housing sector activity will influence the construction sector’s future trajectory.
Monetary Policy Implications & Bank of Canada
Despite the weaker GDP numbers for October, Valencia believes the data is unlikely to prompt a change in course for the Bank of Canada. The Bank of Canada’s Governing Council has already stated that the current interest rate is appropriate for maintaining inflation close to the 2% target and guiding the economy through a period of trade-driven structural adjustment. Therefore, the October GDP data doesn’t significantly “move the monetary policy needle.”
November Outlook & Flash Estimate
Preliminary data from Statistics Canada for November indicates a potential turnaround, with anticipated gains in educational services, construction, and transportation/warehousing – likely due to the resolution of the postal worker strikes. However, persistent weakness remains in resource extraction and manufacturing. The flash estimate suggests a recovery in sectors impacted by temporary disruptions, but doesn’t signal a broad-based economic recovery.
Data & Statistics
- October GDP: -0.3%
- September GDP: +0.2%
- Retail Trade: Down for the second consecutive month.
- Wholesale Trade: Down for the second time in three months.
- Bank of Canada Inflation Target: 2%
Logical Connections
The conversation progresses logically from a broad overview of the GDP decline to a detailed examination of specific sectors. The analysis moves from identifying potential causes (tariffs, strikes) to assessing the implications for monetary policy. The discussion then transitions to a preliminary look at November data, providing a more nuanced perspective on the economic outlook. The consistent emphasis on the need for further data reinforces a cautious and analytical approach.
Notable Quotes
- “One data point isn’t necessarily, you know, a signal, a start of a new trend. Obviously, we’d have to wait for more data to see if this weakness persists in the coming months.” – LJ Valencia
- “The latest monthly GDP data for October doesn't really move the monetary policy needle much.” – LJ Valencia
- “The Bank of Canada and the Governing Council has reiterated that the interest rate is appropriate enough as it is to keep inflation close to 2% target, and also to guide the economy as it undergoes through this period of trade driven structural adjustment.” – LJ Valencia
Synthesis & Conclusion
The Canadian economy experienced a temporary setback in October, with a GDP decline influenced by factors like tariffs on wood products and temporary disruptions like strikes. While these factors contributed to the weakness, the overall outlook remains cautiously optimistic, with a potential turnaround indicated by preliminary November data. The Bank of Canada is currently expected to maintain its current monetary policy, prioritizing inflation control and guiding the economy through ongoing structural adjustments. Continued monitoring of economic data is crucial to assess the sustainability of any emerging trends and inform future policy decisions.
AI summaries can miss context or contain errors. Check important details against the original video.