Key Concepts
- Opening Range Breakout (ORB) Strategy: A trading strategy that identifies a price range during the initial period of a trading session and enters a trade when the price breaks out of this range.
- Opening Range: The price range (high and low) established during a predetermined period after the market opens.
- Breakout: The event where the price moves decisively above the opening range high or below the opening range low.
- Zero-Day to Expiration (0DTE) Options: Options contracts that expire on the same day they are traded.
- Backtesting: The process of simulating a trading strategy on historical data to evaluate its potential performance.
- Short Put Spread: An options strategy that involves selling a put option and buying another put option with a lower strike price, typically used when expecting the underlying asset to rise or stay stable.
- Profit Factor: A measure of profitability calculated by dividing gross profits by gross losses. A profit factor greater than 1 indicates profitability.
- Win Rate: The percentage of trades that result in a profit.
- Max Drawdown: The largest peak-to-trough decline in the value of an investment or trading account over a specific period.
Understanding the Opening Range Breakout (ORB) Strategy
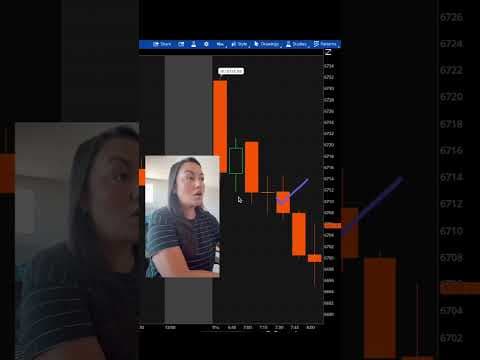
The video introduces the Opening Range Breakout (ORB) strategy, a concept that the presenter, Kirk from Optional Alpha, has historically avoided due to its day-trading nature but is now exploring with the advent of automation and backtesting tools. The core idea of ORB is to define a specific time period after the market opens (e.g., 15, 30, or 60 minutes) and establish the high and low price points within that period. This range then serves as a benchmark to identify potential trading opportunities when the price breaks out of it.
Key Points:
- Personal Journey: Kirk is documenting his personal exploration of the ORB strategy, aiming to find what works for him and sharing the process.
- Automation's Role: The presenter emphasizes that automation makes ORB strategies more attractive, overcoming the manual trading challenges of patience and execution speed.
- Defining the Opening Range: The opening range is determined by the highest and lowest prices achieved within a chosen time frame after the market opens (e.g., 9:30 AM to 9:45 AM ET for a 15-minute range).
- Breakout Trigger: A trade is initiated when the market price moves beyond the established high or low of the opening range.
- Momentum Assumption: The primary assumption behind the ORB strategy is that a breakout in a particular direction will be followed by continued momentum in that same direction for the rest of the trading session.
Manual vs. Automated ORB Trading
The presenter highlights the practical difficulties of manually trading the ORB strategy, which was a primary reason for his past avoidance.
Key Points:
- Time and Patience: Manually monitoring the market for 15 minutes, identifying ranges, and executing trades requires significant time, patience, and skill, which Kirk admits he lacked.
- Automation Advantage: Automation, through platforms like Option Alpha, simplifies the process of defining ranges, monitoring for breakouts, and executing trades, making the strategy more accessible.
Variations in Opening Range Definition
The duration of the opening range period can significantly impact the established high and low, and consequently, the breakout points.
Examples:
- 15-Minute Range: A shorter range might lead to earlier breakouts but potentially less defined price levels.
- 30-Minute Range: Provides a slightly wider window to establish the range.
- 60-Minute Range: A longer range can result in a wider price band, potentially setting a higher threshold for a breakout and delaying its occurrence. For instance, a 60-minute range might have a significantly higher high compared to a 15-minute range, pushing the breakout point later in the day.
Breakout Directions and Assumptions
ORB strategies can be applied to both upward and downward price movements.
Key Points:
- High Breakout: Occurs when the price moves above the opening range high. The assumption is continued upward momentum.
- Low Breakout: Occurs when the price moves below the opening range low. The assumption is continued downward momentum.
- Flexibility in Testing: The presenter notes that while the upward breakout is a traditional approach, backtesting can explore strategies for both high and low breakouts.
Backtesting the ORB Strategy on Option Alpha
The video demonstrates how to set up and run a backtest for a basic ORB strategy using the Option Alpha platform, specifically for Zero-Day to Expiration (0DTE) options on SPX.
Step-by-Step Process:
- Platform Selection: Access the Zerodite backtester within Option Alpha.
- Instrument and Strategy: Select SPX and choose a "short put spread" strategy, as the initial test aims to profit from an upward breakout.
- Strike Selection (Short Put):
- Utilize a recipe that includes opening range variables.
- Set the short strike to be "$1 below" the opening range high. This positions the short put just below the expected breakout point, aiming to capture momentum if the price moves higher.
- The option chosen is the "closest strike to $1 below the market and or lower," ensuring it's not already in the money.
- Strike Selection (Long Put):
- Set the long put strike "$5 below" the short put to create a "$5 wide spread" for SPX, a common practice for risk management.
- Capital and Contract Size: Set basic parameters like $10,000 capital and one contract at a time.
- Position Entry (ORB Specifics):
- Opening Range Period: Select the desired period (e.g., 15 minutes). Other options include 5, 10, 30, and 60 minutes.
- Direction of Breakout: Choose "above the high" for this test.
- Latest Entry: Define the latest time the bot will consider entering a trade after a breakout. The presenter suggests avoiding very late entries (e.g., after noon) due to potential premium decay and market volatility.
- Range Width Filters:
- Max Opening Range: Set a maximum percentage (e.g., 1%) for the opening range. If the range is too wide, it might indicate excessive volatility, and the trade is skipped.
- Min Opening Range: Set a minimum percentage (e.g., 0.5%) for the opening range. A very narrow range might lead to whipsaws. The goal is to find a balance.
- Trading Days: Select "all trading days."
- First Breakout Only: Check this box to prevent the bot from entering multiple trades on subsequent breakouts in opposite directions.
- FOMC and Slippage: Skip FOMC days and always include slippage.
- Profit Taking: For this initial test, profit-taking is set to "run it to expiration."
- Backtest Duration: Set the backtest period to three years to gather sufficient data.
- Run and Analyze Results: Execute the backtest and review the performance metrics.
Backtest Results and Analysis
The initial backtest of the 15-minute ORB strategy on SPX 0DTE short put spreads yielded interesting results.
Data and Findings:
- Profitability: The strategy was profitable over the last three years.
- Profit Factor: 1.08, indicating slightly better than dollar-for-dollar returns.
- Win Rate: 64%, which the presenter interprets as supporting the assumption that higher breakouts generally lead to continued upward momentum.
- Number of Trades: 314 trades over three years.
- Filtered Trades: A significant number of trades were filtered out due to various reasons:
- No breakout occurred.
- Opening range was the range of the day.
- Breakouts below the minimum opening range (too little movement).
- Breakouts above the maximum opening range (too much volatility).
- FOMC days.
- Late breakouts.
- Early market closes.
Comparing Variations: Narrower Range Test
To further refine the strategy, a comparison was made by testing a variation with a narrower opening range requirement.
Comparison:
- Test B: Allowed for narrower entries after a breakout of a narrower range (0.5% range).
- Results: Strategy B was less profitable, with a reduced profit factor, a bigger max drawdown, and a lower win rate.
- Insight: This suggests that allowing the market to move a bit more before a breakout (wider range) might lead to better quality signals and entries, even if it results in fewer trades. The hypothesis is that trading less but getting better signals is more effective.
Conclusion and Next Steps
The video concludes by emphasizing the value of backtesting and the iterative process of refining trading strategies.
Key Takeaways:
- The ORB strategy, when automated, can be a viable approach for 0DTE options traders.
- Backtesting is crucial for validating hypotheses and identifying optimal parameters.
- The initial backtest suggests that the assumption of continued momentum after a breakout holds some validity, as indicated by the win rate.
- Further testing and comparison of different ORB parameters (range duration, width, entry timing) are planned for future videos.
- The presenter encourages viewers to engage with the content and share their own findings.
AI summaries can miss context or contain errors. Check important details against the original video.