OpenAI Diversifies Chip Suppliers & Broader Tech Trends
Key Concepts:
- Inference vs. Training: The distinction between the initial training of an AI model (a one-time cost) and its ongoing operation for users (a recurring cost).
- TPUs (Tensor Processing Units): Custom AI accelerator chips developed by Google.
- Blackwell: NVIDIA’s latest and most advanced GPU, considered the “gold standard” in AI hardware.
- Chip Diversification: The trend of AI companies moving beyond reliance on NVIDIA GPUs and exploring alternative chip suppliers.
- Memory Chip Scarcity: Shortages and market dynamics in the memory chip industry, including increased demand from Chinese manufacturers.
AI Chip Landscape & OpenAI’s Shift
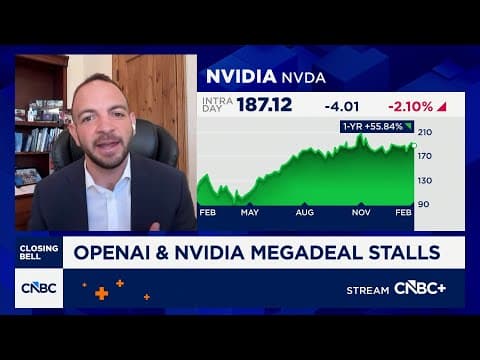
The report centers on OpenAI’s recent decision to utilize chips from Cerebrus for running its latest AI model, GPT-5.3 Kodak Spark. This marks a significant departure from OpenAI’s previous reliance on NVIDIA GPUs and signals a broader industry trend of diversifying chip suppliers. While OpenAI remains a major NVIDIA customer, the move is framed as “dating other people” – a diplomatic acknowledgement of exploring alternatives.
This shift is particularly focused on inference, the process of running a trained model for end-users. Deirdre Bosa emphasizes that inference costs are recurring and will likely represent the majority of compute spending as AI products scale, making cost optimization crucial. OpenAI’s GPT-5.3 Kodak Spark is described as a “lighter and faster” model, suggesting a focus on efficiency and scalability for widespread adoption, prioritizing the “workhorse” revenue-generating model over the “flagship” prestige model.
Industry-Wide Diversification & NVIDIA’s Position
OpenAI isn’t alone in this diversification effort. Google has already deployed its own TPUs for Gemini 3, and Chinese AI lab GPU released GLM trained on Huawei chips. Meta and Microsoft are also developing their own AI chips, albeit primarily for internal use. Reuters reported that OpenAI expressed dissatisfaction with some of NVIDIA’s latest chips specifically for inference tasks.
Despite this, NVIDIA’s Blackwell GPUs remain the “gold standard” and are still highly sought after by all major AI labs. However, companies are actively signing deals with Cerebrus, Broadcom, and AMD to reduce their dependence on a single supplier. The investor narrative is shifting, with infrastructure spending continuing but being distributed across a wider range of chip manufacturers. NVIDIA is identified as potentially having the most to lose in this evolving landscape.
Quote: “It’s a diplomatic way of saying we love Jensen [Huang, NVIDIA CEO], but we’re dating other people now.” – Deirdre Bosa, commenting on OpenAI’s statement regarding NVIDIA.
Data & Statistics:
- Walmart’s stock is up 20% year-to-date (as of the broadcast date).
- Cisco experienced its fifth-worst day in 25 years (likely related to memory chip issues).
Memory Chip Market Dynamics
The discussion expands to the memory chip market, noting a broadening story beyond Dell and HP, now impacting Apple and Cisco. A key point is the increasing competitiveness of Chinese memory chip manufacturers, particularly in the lower end of the market. American companies are reportedly seeking to purchase Chinese memory chips to address supply shortages and potentially lower costs. This highlights a broader trend of China improving its capabilities in chip manufacturing, filling gaps in the global supply chain.
Quote: “There’s a piece a few weeks ago about American companies actually wanting to buy Chinese memory chips.” – Deirdre Bosa, highlighting the changing dynamics in the memory chip market.
Consumer Sector & Leadership Turnover
The segment briefly transitions to the consumer sector, anticipating Walmart’s earnings report and noting the strong performance of its stock (up 20% year-to-date). The report also highlights a significant trend of leadership turnover in major consumer companies, including Walmart, Target, Nike, Lululemon, and Bath & Body Works.
Logical Connections:
The report establishes a clear connection between the high cost and limited availability of NVIDIA GPUs and the drive for chip diversification. The memory chip discussion demonstrates a similar dynamic of supply chain vulnerabilities and the emergence of alternative suppliers. The transition to the consumer sector serves as a brief pivot to another area of market activity.
Synthesis/Conclusion:
The core takeaway is that the AI industry is actively diversifying its chip supply chain, driven by cost considerations, supply constraints, and a desire to avoid over-reliance on a single vendor (NVIDIA). While NVIDIA remains a dominant player, particularly in the high-end GPU market, the trend towards in-house chip development and partnerships with alternative suppliers like Cerebrus, Broadcom, and AMD is gaining momentum. This shift is also mirrored in the memory chip market, with Chinese manufacturers playing an increasingly important role. The report underscores a dynamic and evolving landscape in the technology sector, characterized by both competition and collaboration.
AI summaries can miss context or contain errors. Check important details against the original video.